
 Daniel Black
One rejected approach, a threat of legal action from lenders and an administration. That’s what it took for BT to land TalkTalk this week.
In the end it bought the business and PlatformX debt-free, adding c.2.5m customers, and the CMA had an inquiry open within hours.
In this week’s editorial, we look at UK public M&A, where size is no longer a defence. Prologis’ £14.3bn bid for SEGRO is the largest deal since 2018, and SEGRO is the sixth FTSE 100 company to accept an offer this year. Yet bidders are aiming high without overpaying, with average premiums down to 36.93% from 51% in 2023.
In the Rumour Mill, Axis Capital has floated €3.20 a share for PTSB, above BAWAG’s agreed €2.97. Kenmare Resources shares jumped 29% after an approach from IRH.
The Deal Tracker features 38 transactions this week. Three stood out:
- Informa is buying Clarion Events from Blackstone for £2.24bn. That brings ICE Barcelona and DSEI into its portfolio while it lines up a separation of Taylor & Francis.
- Ithaca Energy is paying up to $1.11bn for Suncor’s Terra Nova and White Rose stakes offshore Canada.
- CareTrust REIT agreed a c.£1.1bn pipeline deal for 45 UK care homes from LNT.
Thanks for reading, and connect with me on LinkedIn if you want to discuss how I can help with your next M&A deal.
Share your views on data room prices for a chance to win $150
One M&A advisor recently received a €90,000 invoice from his virtual data room provider, nearly four times the original quote. We suspect he’s not alone.
We’re surveying dealmakers across the M&A Community to find out how common hidden VDR costs really are. Share your experience in just two minutes.
As a thank you, everyone who takes part will be entered into a prize draw for a $150 Amazon voucher. All responses are confidential.
Weekly summary | 09.10.2026
This week’s Deal Tracker captures 37 transactions. Business services was the busiest sector with seven deals, followed by energy and resources with five. The biggest ticket was the £6.7bn takeover of Boots by Canada’s Weston Family, alongside Fairfax Financial Holdings.
Healthcare brought the other large cheques. AstraZeneca completed its $2bn equity investment in Summit Therapeutics, and CareTrust REIT agreed a c.£1.1bn pipeline deal for 45 UK care homes from LNT. Nova Capital’s purchase of BMP Group and RB Medical and Welford’s acquisition of a Belper care home show how active the sector is in the mid-market too.
Technology deals were smaller but more frequent. Sage made two bolt-ons in France, buying AI studio WholeHelp and Moovin’Cloud’s cloud platform. Analysys Mason added Swedish AI consultancy Modulai, and Kortext bought StudyStash just a year after the platform launched.
In energy, Ithaca Energy is paying $860m plus up to $250m in contingent payments for Suncor’s Terra Nova and White Rose stakes offshore Canada. Actis added 244MW of battery storage in Poland. Not everything got over the line: Reabold’s offer for Union Jack Oil lapsed at 13.02% acceptances.
Finally, BT bought TalkTalk out of administration, adding c.2.5m customers. The CMA has already opened an inquiry, so this deal isn’t done with the regulators yet.
Size is no longer a takeover defence
For years, sheer size was the best defence a UK plc had. Big balance sheets put off bidders, as did big shareholder registers and big price tags. In 2026, that is no longer true.
The biggest names are now in play
Prologis’ £14.3bn offer for SEGRO is the largest Takeover Code deal since 2018, according to Gibson Dunn’s latest UK Public M&A: The Month in a Minute. SEGRO is also the sixth FTSE 100 company to accept an offer this year.
Bidders are not waiting to be invited, either. Harworth was the fifth hostile bid of 2026, more than in any full year of the last decade.
A summer surge
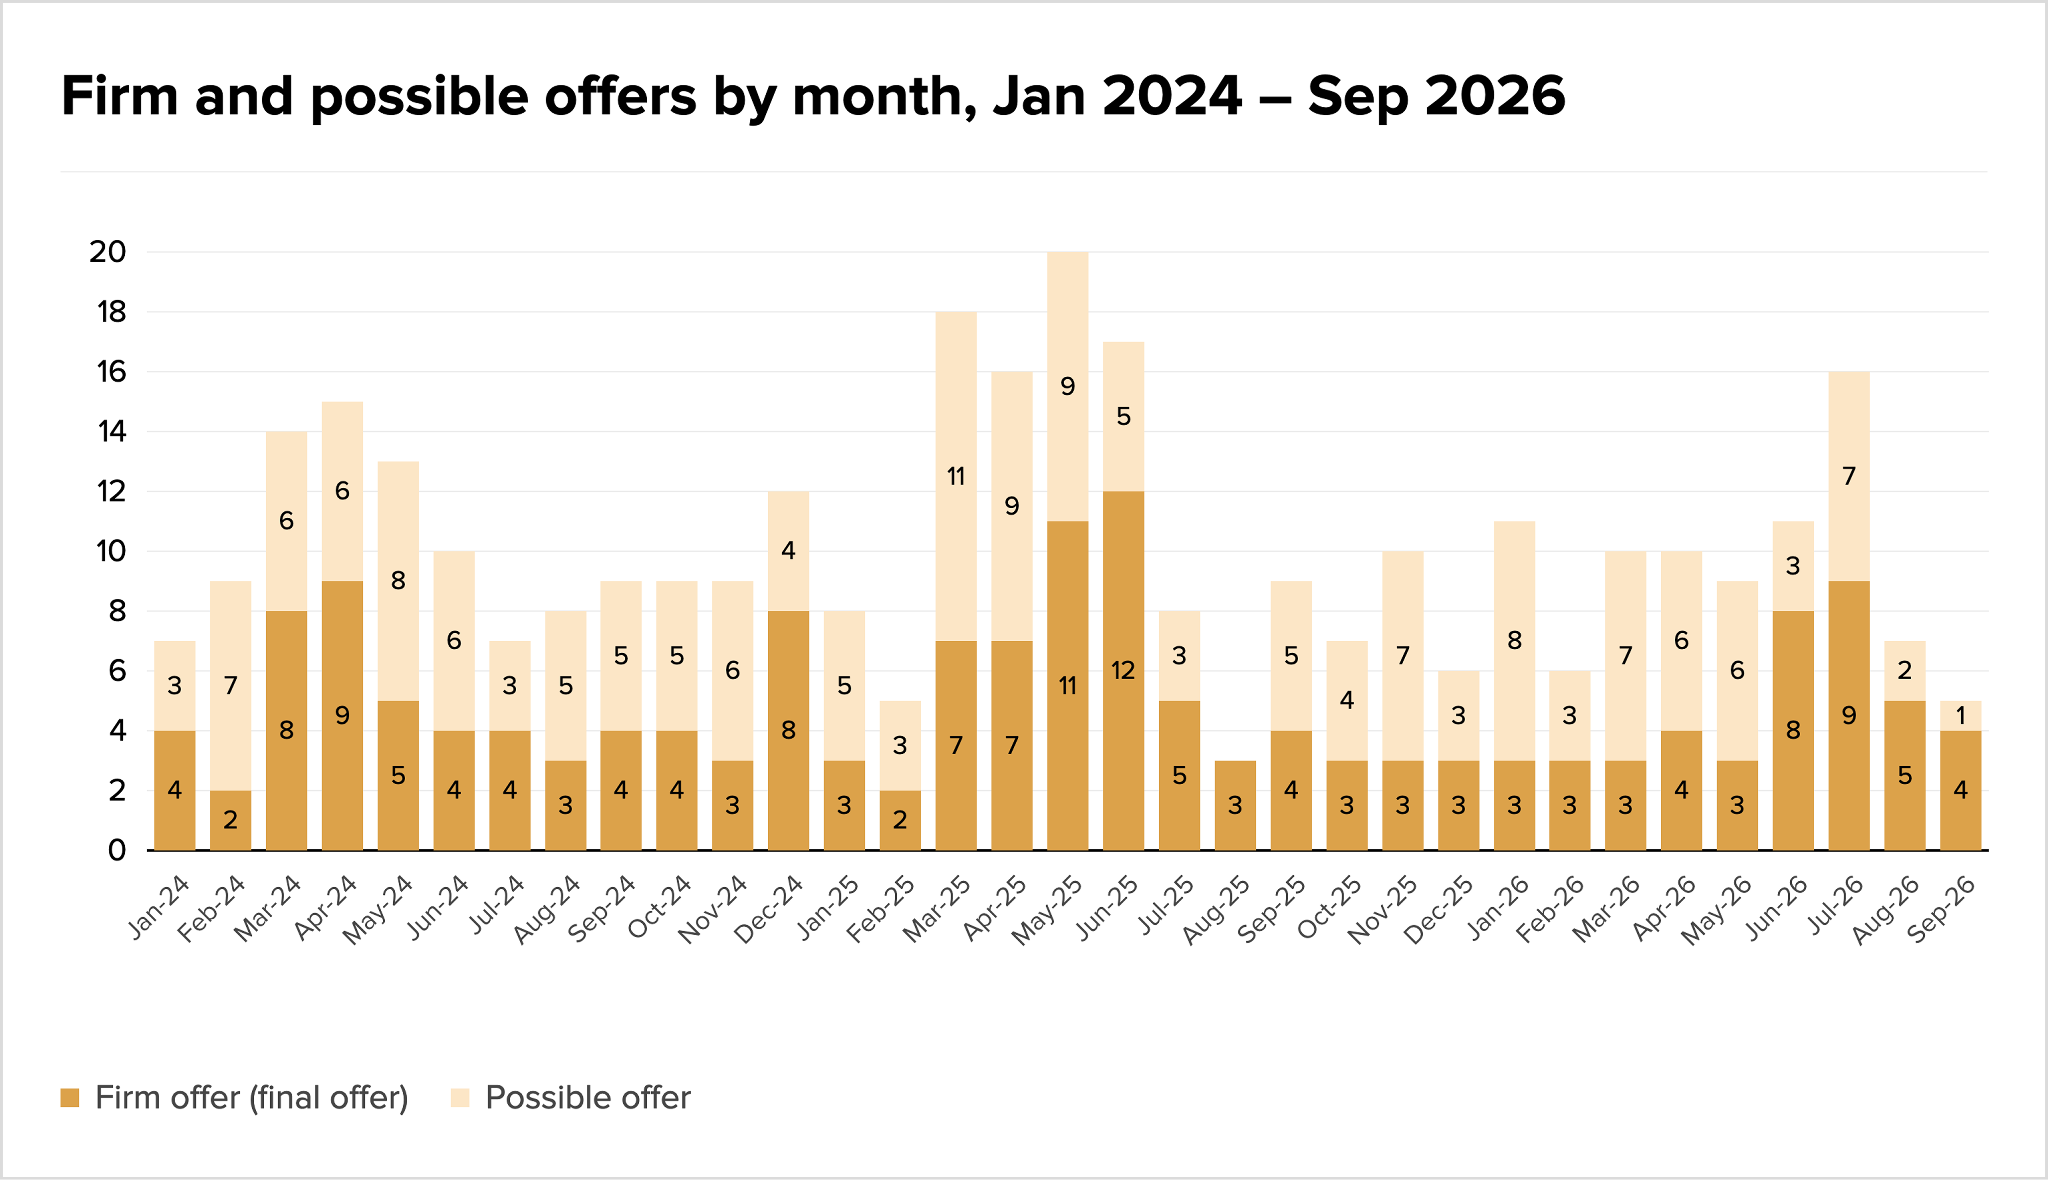
The pipeline backs this up:
- Eight firm offers in June and 9 in July, the busiest run since mid-2025
- July also brought seven possible offers, a sign of more approaches still to come
- August and early September were quieter, although September was only half over when the report was published
But nobody is overpaying
This is where it gets interesting. Bigger targets have not meant richer bids.
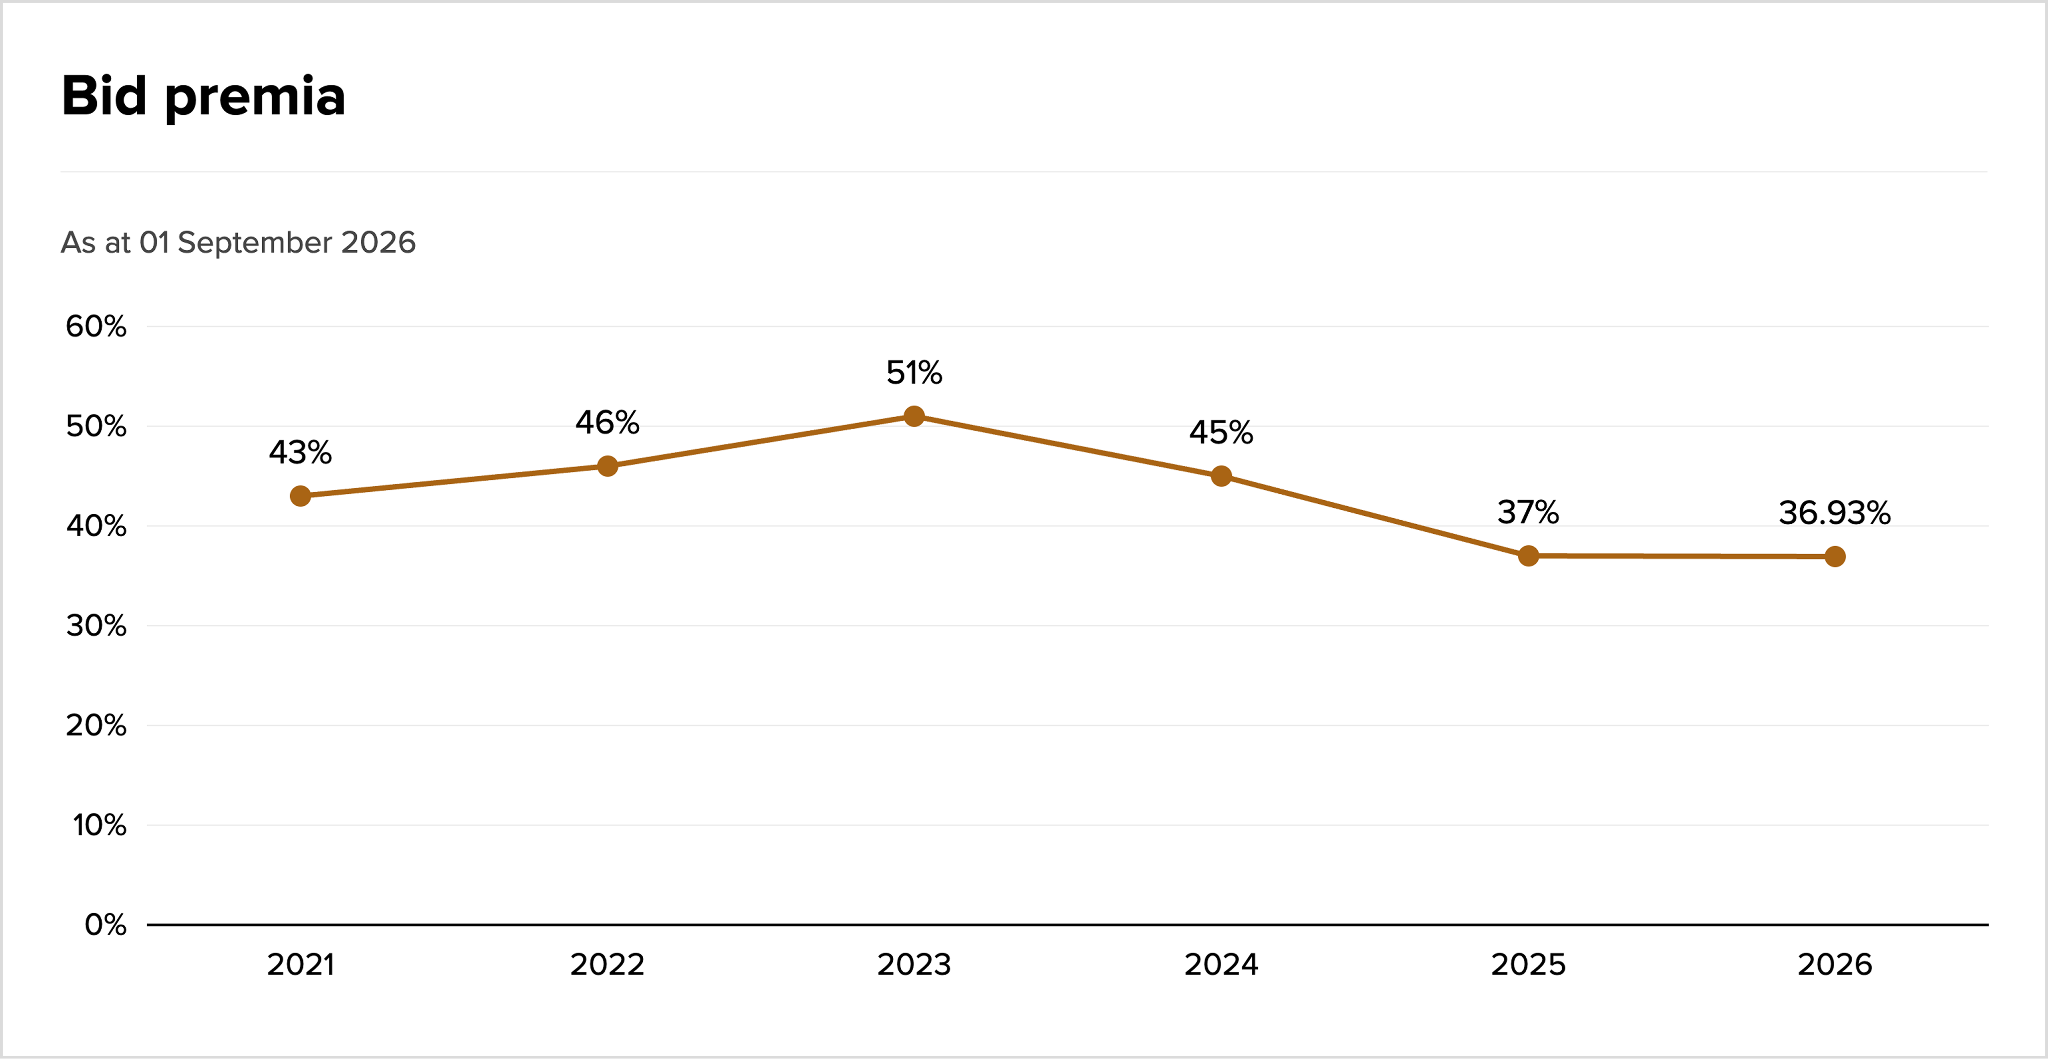
The average bid premium stands at 36.93% in 2026, down from a peak of 51% in 2023 and broadly flat on last year. Bidders are aiming higher but paying less to get there.
Why it matters
Two forces seem to be at work. UK valuations are still low enough that a modest premium can look generous to shareholders. Boards, meanwhile, know that a big market cap no longer guarantees independence and that hostile bids are now a realistic option.
For targets, being big is no longer a defence in itself. A credible standalone plan is what counts now. For bidders, the window is open, but discipline on price is clearly part of the playbook.
The question for Q4: will premiums climb as competition for large assets increases, or are lower premiums here to stay?
Rumour mill
- Kenmare Resources shares jumped 29% after the Irish mineral sands miner confirmed a non-binding possible cash offer approach from International Resources Holdings (IRH). The put-up-or-shut-up deadline is 17 November 2026.
- 80 Mile and Greenland Energy have extended the put-up-or-shut-up deadline for Greenland’s possible all-share offer to 3 November 2026.
- Sainsbury’s held merger talks with Morrisons between November 2025 and February 2026 before walking away, the FT reports. The combined group would have held c.23.6% of the UK grocery market.
- Axis Capital has floated a possible €3.20-per-share cash offer for PTSB, above BAWAG’s agreed €2.97 scheme. PTSB says no offer has been made, and the High Court sanction hearing for the BAWAG deal is set for late October.
- Bahrain’s BBK is in talks to buy a 20% stake in City stockbroker Panmure Liberum.
- ConocoPhillips says it has not yet decided on an unsolicited offer for its Norwegian business and its UK Teesside terminal.
- Better Home & Finance is moving towards a sale of Birmingham Bank to a B Singh Partners-led consortium at 0.95x tangible net asset value (TNAV of c.£56m), with £10m in escrow. The deal has not yet been signed.
- Tesco has joined the auction for Fortress-owned Majestic Wine in a deal that could be worth around £100m, Sky News reports.
- Steve Madden is looking to sell Kurt Geiger’s concessions business, according to Sky News.
- Monzo is turning to private equity, including TPG, after Nubank ended takeover talks.
- Ireland-domiciled Accenture plans to spend around $5bn on acquisitions over the next year, with AI capabilities a focus.
Regulatory
- The court has sanctioned Senior plc’s scheme of arrangement for its c.£1.3bn takeover by Tinicum and Blackstone (Zeus UK Bidco). The scheme takes effect on 8 October, with delisting expected on 9 October.
- India’s Competition Commission (CCI) has approved the acquisition of sole control of Omega-Meyer Limited and Meyer Organics by funds advised by Bain Capital.
- The CMA has opened a Phase 1 inquiry into BT’s acquisition of TalkTalk, issued an initial enforcement order and followed it with a pre-emptive action order on 6 October. Its report to the Secretary of State is due on 19 October.
- The CMA’s interim report finds that the £2bn Nexfibre/Netomnia broadband deal may substantially lessen competition. Remedies are due by 16 October and a final decision by 15 December.
- China is demanding copper supply commitments from Anglo American and Teck as a condition for approving their merger, Reuters reports.
- London-based investor Lightrock is seeking CCI approval in India for its stake in Mahindra Last Mile Mobility, following the Lightrock-led funding round that valued the EV maker as a unicorn.
- Circle8 made a revised proposal to SThree regarding an improved all cash offer
- The acquisition of Gumtree.com by FE International Ltd has been approved subject to conditions.
Job moves
- Wilmington: Sophie Tomkins is stepping down from the board, with Christopher Humphrey taking over as Chair of the Audit Committee.
- Waystone has named James Bowers (ex-Principal Asset Management, Janus Henderson) CEO of its UK ACD business and hired Allan Seldon (ex-Tutman) as MD, Client Solutions. Karl Midl remains UK Country Head.
- Executive talent platform True has hired Tracy Zhang, formerly of T-DRIVE, as a London-based partner to expand its global tech leadership practice.
- Temple Bar Investment Trust director Shefaly Yogendra has been appointed a non-executive director of Fidelity Emerging Markets.
- AQSE-listed Reveille Resources, which is focused on Italian uranium, has proposed former US Secretary of State Mike Pompeo as non-executive chairman, subject to conditions. Andrea Cattaneo becomes deputy chair.
- Vertical Aerospace has appointed Clyde Woltman, former CEO of Leonardo Helicopters U.S., to its board.
- Pemberton Asset Management has appointed a new head of its €1.6bn CLO platform.
- Moore Kingston Smith has hired David Smithson as a restructuring partner. He brings 37 years of experience.
- Griffin Mining has appointed Asha Santchurn as CFO. Roger Goodwin steps down as Finance Director but remains a director and company secretary.
- Care software firm Birdie has appointed Alastair Douglas as CEO, with co-founder Max Parmentier becoming Chair.
- Wolf Theiss has opened London support for investors across CEE/SEE, led by partner Anna Dąbrowska, previously head of M&A in Warsaw.
- I Squared Capital has hired Radu Gruescu as a Managing Director in its European energy transition team.
- Eversheds Sutherland has hired Andrew Fordham from Addleshaw Goddard.
- Moneypenny CEO Jesper With-Fogstrup is stepping down to take on a new role.
- AI cloud group Nscale has hired Meta’s Justin Osofsky as COO ahead of a planned IPO.
- M&A advisory Carlsquare has appointed Jamie Edge as partner.
- HSBC has hired Cantor Fitzgerald’s Paras Jain to lead its global TMT banking business, sources say.
- Fellwood Advisory, part of Cooper Parry, has hired Saran Lall (Director, Midlands) and Molly Pearson (Associate Director, London), both from KPMG’s debt advisory team.
- Beazley CEO Adrian Cox is stepping down as Zurich completes its acquisition of the specialty insurer.
- RBC Wealth Management has appointed William Hepburne-Scott as Chief Commercial Officer.
- WilmerHale: Jeremy Kosky now heads the London disputes practice.
- DFS has appointed Liz McMeikan as non-executive director and Chair Designate. She will succeed Steve Johnson in 2027.
- KPMG corporate finance partner Rick Stark is leaving the firm after more than 20 years.
- WilmerHale has hired Charlie Lightfoot as a partner in its international arbitration practice in London.
Fundraising
- eEnergy Group has closed its fundraise at c.£8.3m after a £1.96m retail offer topped up the earlier £6.3m placing and subscription. Trading in the AIM-listed energy services group’s shares has been restored.
- Severn Trent Utilities Finance has priced two note issues: €100m 4.000% notes due 2034 and £70m 5.926% notes due 2031.
- Informa has raised £940m through an equity issue to part-fund its £2.24bn acquisition of Clarion Events.
- Edinburgh Investment Trust has signed a new £25m one-year multicurrency revolving credit facility with ICBC London to provide additional gearing.
- The British Business Bank has increased its ENABLE Build guarantee facility with Shawbrook to £350m, supporting lending to housebuilders and developers.
- B.P. Marsh & Partners has taken a 30% stake in Dauntless U/W, a new London marine hull MGA, for nominal consideration and has provided a £2.0m loan facility.
- Avacta Group has raised £12.5m through a placing and subscription at 68p, extending its cash runway into Q2 2027.
- Cambridge-based Reclinker has raised £10m to scale its technology for producing cement from demolition waste.


