
 Daniel Black
The ONS published its Q2 numbers earlier this month, and they tell two stories at once.
Foreign buyers spent £25.4bn on British companies, roughly two and a half times what they spent a year earlier. Meanwhile UK companies buying other UK companies fell to 130 deals, the lowest in the four-year series.
Do the maths and the average inward deal came in at around £157m, against roughly £48m in Q2 2025. Engie took UK Network Holdings. Eli Lilly took Centessa Pharmaceuticals. That is concentration rather than a broad repricing, but the direction of travel is hard to miss.
This week made the point twice over. Goodwin agreed to sell a substantial part of its Mechanical Engineering division to Cerberus for up to £1.1bn in cash, a business that made £69m of operating profit last year and now heads to a US owner.
And Spire Healthcare, Britain’s largest private hospital operator, agreed a £1.03bn take-private with a group led by Toscafund, after Bridgepoint and Triton both walked in March.
Three more eye-catching stories from this week:
- EQT is buying specialty broker McGill and Partners from Warburg Pincus for $2.0bn, part of a genuinely busy stretch for insurance M&A.
- Waterland is lining up a rival bid for Gamma Communications, threatening the £1.08bn deal Epiris already has agreed.
- Voneus bought rural broadband rival Airband out of administration. Every job saved, and backers roughly £200m down.
And in funding: ICG closed its ninth European Corporate fund at a record €12bn, while Bridgepoint Credit completed a €1.2bn continuation vehicle led by Pantheon.
Thanks for reading, and connect with me on LinkedIn if you want to discuss how I can help with your next M&A deal.
Weekly summary | 11-09-2026
The Deals Tracker logs 50 announced transactions this week, with a disclosed value of roughly £5.4bn across the minority of deals that put a number on it. Energy and natural resources led on volume with around 15deals, but the largest is industrial: Goodwin’s sale of its Mechanical Engineering division to Cerberus for up to £1.1bn.
Four deals cleared the £1bn mark. Alongside Goodwin, Spire Healthcare agreed a £1.03bn take-private with a Toscafund-led group, and EQT is buying specialty broker McGill and Partners from Warburg Pincus for $2.0bn. Diversified Energy’s $1.8bn purchase of Birch makes four.
The Goodwin deal is the one to read properly. Cerberus is taking Goodwin Steel Castings, Goodwin International, Noreva GmbH, Easat Group and the Pumps Division, a unit that produced £210m of revenue and £69m of operating profit in the year to April. Completion is expected in Q1 2027, subject to National Security and Investment Act clearance. Rothschild advised Goodwin, with UBS and JPMorgan on the Cerberus side.
Insurance kept its pace. Four transactions again this week: EQT and McGill, Tokio Marine HCC’s agreement to buy Chelmsford-based Direct Commercial, TDC-backed Tower opening a buy-and-build toward £100m of gross written premium, and Shackleton adding AC Wealth in Scotland.
Energy and resources carried the volume. Qualitas Energy took Cero Generation’s 5.8GW solar and storage platform off Macquarie, Foresight bought the Blackhillock synchronous condenser, and Eelpower picked up the Silkstead battery project. Shell alone accounted for three transactions.
On the funding side, private credit dominated. ICG closed its ninth European Corporate fund at a record €12bn, Jefferies Credit Partners announced $4bn of European direct lending capacity anchored by Allianz Global Investors, and Bridgepoint Credit completed a €1.2bn continuation vehicle led by Pantheon.
The British Business Bank appeared three times, backing funds in the North, the South East and Zinc’s deeptech vehicle.
The UK is being bought, not buying
The Office for National Statistics published its Q2 numbers on September 1, and they split cleanly in two directions.
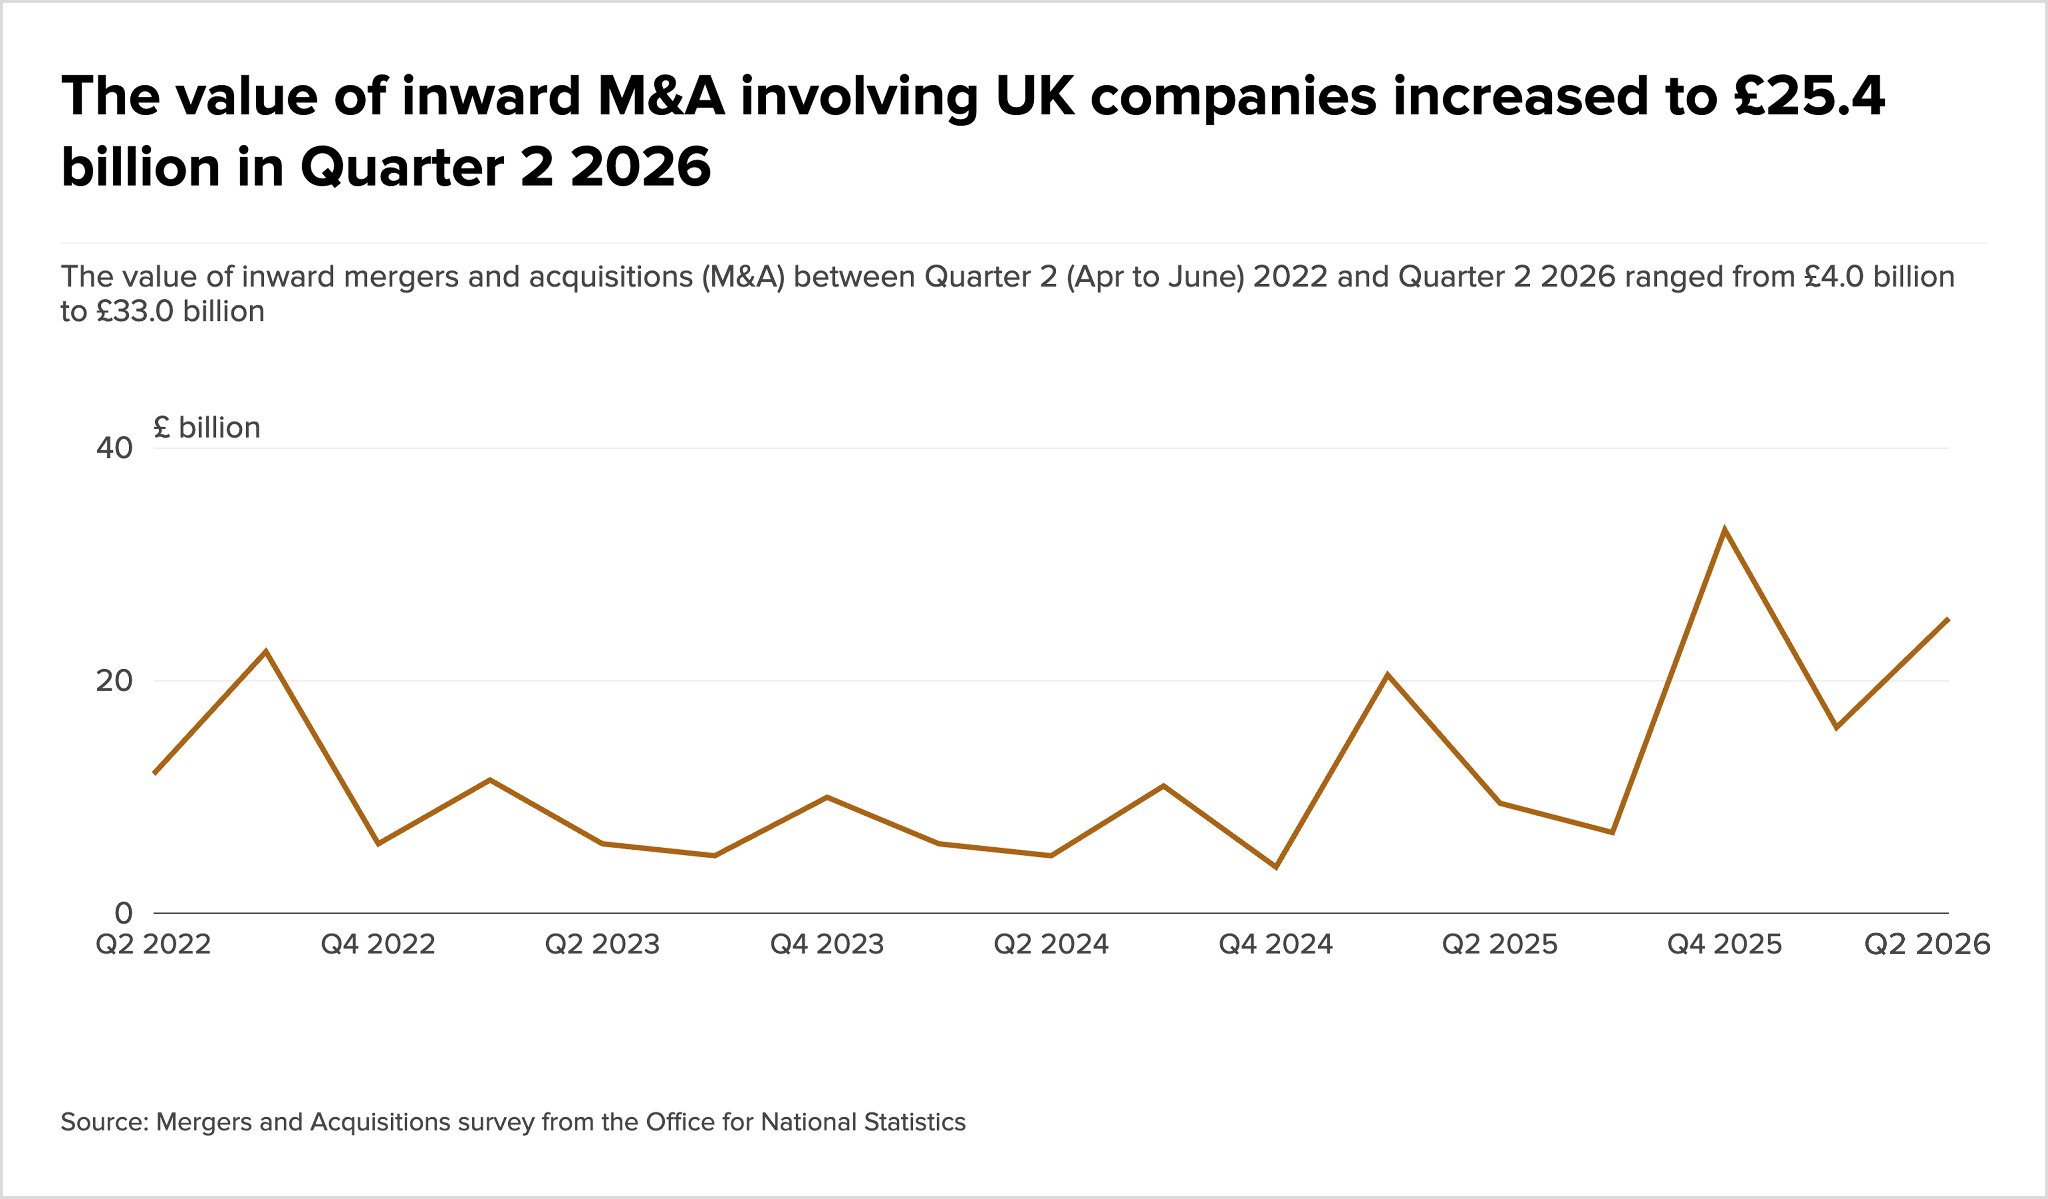
Foreign money is pouring in. Inward M&A hit £25.4bn, up from £15.7bn in Q1 and £9.7bn a year ago. That’s roughly two and a half times the value of Q2 2025.
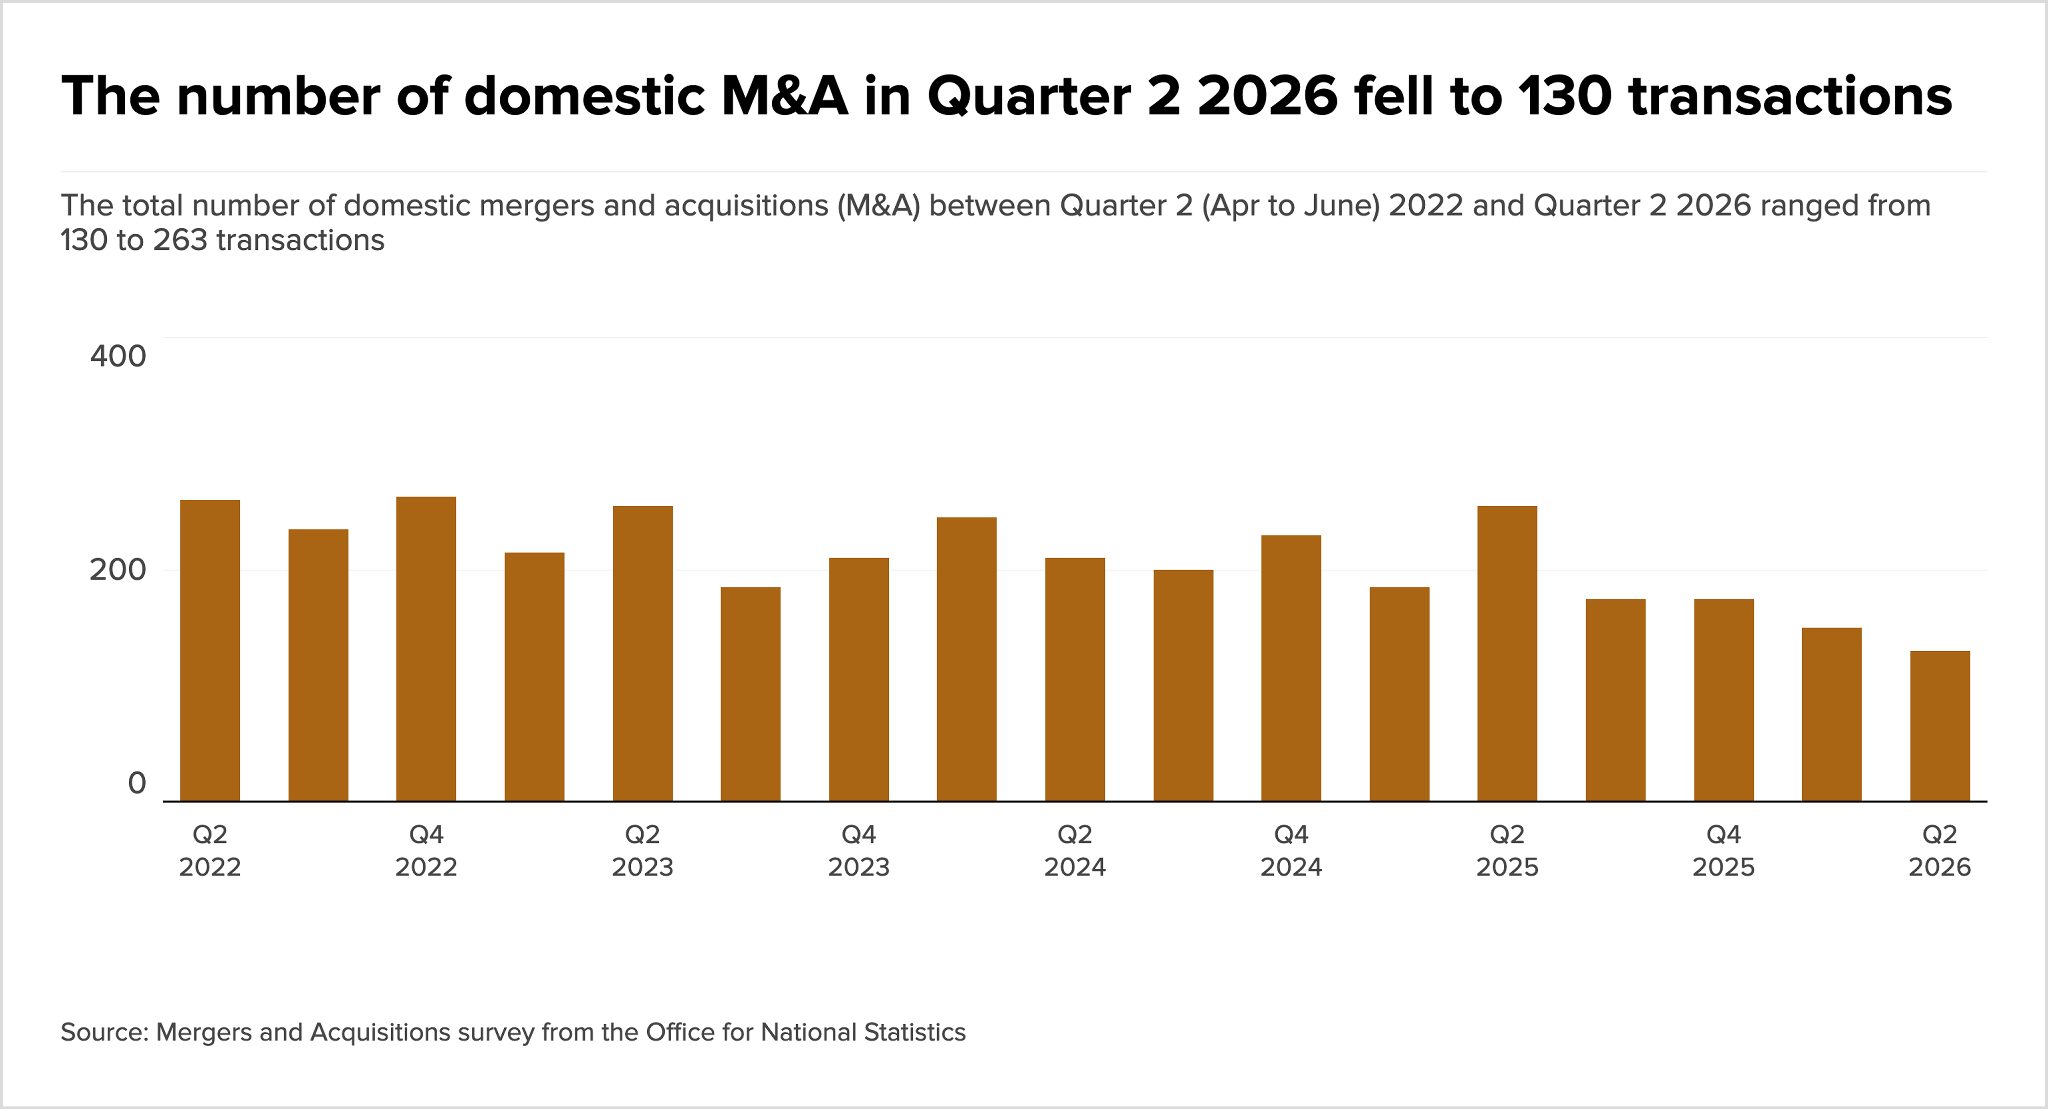
Domestic dealmaking has gone quiet. UK companies buying other UK companies fell to 130 transactions – down from 241 a year earlier, and the lowest bar in the four-year series ONS shows.
Run the arithmetic on the inward side and the picture sharpens. There were 162 completed inward deals in Q2, against 203 a year earlier. So the average inward transaction was worth roughly £157m, against about £48m in Q2 2025. Foreign buyers are paying far more for far fewer British companies.
Meanwhile UK plc isn’t shopping. Outward M&A fell on both counts: 61 deals worth £2.7bn, both below the previous quarter and the same period last year. Net cross-border flows ran to minus £16.8bn.
Three caveats worth mentioning:
- ONS flags that the high inward-value quarters, this one included, each contained a handful of deals worth more than £1bn. Engie took UK Network Holdings; Eli Lilly took Centessa Pharmaceuticals. This is concentration, not a broad repricing of British assets.
- The figures are provisional, and ONS notes revisions run upward more often than down. The volume lows may soften.
- ONS counts completions, not announcements. This is the rear-view mirror.
That last point matters. Last week’s Deloitte CFO Survey had UK finance chiefs raising expansion by acquisition as a priority from 17% to 22% – while completed domestic deals hit a series low. Not a contradiction, but a sign that an increase in deals might be on the horizon.
What to watch: whether the intent shows up in Q3 completions, or whether the pattern holds – a UK that trades at a discount attractive enough for foreign buyers, and a domestic market too cautious to compete for its own assets.
The Spire Healthcare takeover this week, agreed at £1.03bn by a Toscafund-led group, suggests the discount argument still has legs.
Jobs Highlights
Rumour mill
- SThree responds to media speculation about takeover
- Waterland is lining up a rival bid for Gamma Communications, threatening Epiris’s £1.08bn agreed deal.
- EDF is in talks to buy So Energy as the French utility looks to expand its British customer base.
- Europe’s largest mobile operators are in talks over a joint venture for satellite-to-mobile services, Bloomberg reports.
- DNO confirms it has no intention of making an offer for Genel Energy, ending speculation around the London-listed producer.
- Spire Healthcare agrees a £1.03bn takeover by an investor group led by Toscafund Asset Management at 250p a share, after Bridgepoint and Triton both walked away in March.
- The Very Group looks set to halt its auction after reports its £2bn asking price went unmatched.
- Everton’s owners are seeking investors following the summer rush of football deals.
- Futura Medical launches a formal sale process alongside a fundraise.
- Advisory firm Interpath is hunting an acquisition of its own in the US.
- Samsung’s insurance arms plan to buy Lloyd’s insurer Canopius for $1.5bn, according to the Korea Economic Daily.
- Car dealer Sherwoods is targeting acquisitions after a rise in turnover.
Job moves
- CVC sets out its leadership succession, with Todd Sisitsky and Peter Rutland to become co-chief executives by Q1 2028.
- BKL hires a retail capital markets specialist from Colliers.
- Aberdeen Group announces a change to its board.
- IMI appoints a new non-executive director.
- Renew Holdings appoints a non-executive director and chair designate.
- The Dot Group names a former Cisco and Hines executive as European chief executive of Yugo.
- Polar Capital appoints Fiona Fry and David Melvin as non-executive directors after its 24 September AGM, as Win Robbins steps down after nine years.
- Jupiter Asset Management hires George Ensor and Mayan Uthayakumar from River Global to run its UK SMID range, as Tim Service and Matt Cable depart in early 2027.
- Trinh Tu is appointed Chief Executive of Ipsos in the UK and Ireland.
- Hans Georgeson steps down as chief executive of Royal London Asset Management after five years; group CFO Daniel Cazeaux takes over on an interim basis.
- Literacy Capital appoints Nick Latner, finance director of Hg, as a non-executive director and Audit Committee chair from 22 October.
- AJ Bell appoints Craig Gentle, formerly CFO of St. James’s Place, and Steve Langan as non-executive directors, with three directors stepping down.
- Knight Frank names Chris Davis as Group CFO.
- Virgin Atlantic appoints Richard McCord as chief financial officer.
- Kaizen onboards Rob Bernstein as chief financial officer.
- BP appoints Ian Tyler as chair following boardroom turmoil.
- Patrick Affleck is appointed chief executive of Havas UK and Ireland Village.
IPOs
Fundraising
- ICG closes its ninth European Corporate fund at €12bn, a record for the strategy.
- Jefferies Credit Partners announces $4bn of capacity for its European direct lending strategy, anchored by a first close backed by Allianz Global Investors.
- The British Business Bank launches a £210m investment fund for the South East of England.
- Tether and Fasanara Capital launch a $400m private credit fund for stablecoin-enabled real-economy lending.
- Kapital raises $125m from Tru Arrow Partners and Fasanara Capital.
- CloudNC raises $20m to expand its AI tools for precision machining.
- HelmGuard raises $7.3m for agentic governance, risk and compliance tooling.
- Holcim invests in Cloud Cycle to bring real-time machine learning to concrete delivery.
- Hayfin provides €305m of financing to Spanish supermarket group Condis, with Gomez-Acebo & Pombo advising.
- Rathbones Group issues £60m of new Tier 2 notes.
- SCI Semiconductor raises an oversubscribed £5m led by PXN Ventures and Mercia Ventures through NPIF II, to scale production of its memory-safe ICENI chips.
- Bridgepoint Credit completes a €1.2bn continuation vehicle for its 2017-vintage Direct Lending II fund, led by Pantheon in an oversubscribed process.
- Molten Ventures reaches a £175m first close on its Growth Fund, with the British Business Bank as cornerstone investor.
- The British Business Bank backs a new £150m scale-up fund for the North of England.
- Claret Capital Partners reaches a final close of €575m, making it Europe’s largest independent growth debt manager.
- Jersey Electricity secures a £100m sustainability-linked RCF from Lloyds, NatWest and HSBC alongside a new $150m US private placement shelf facility.
- Pixxel raises $100m in Series C funding to build out its Earth-imaging satellite constellation.
- Ferrexpo raises about $100m in an equity fundraise as its London trading prepares to resume.
- UK AI governance startup AI Score raises $5.4m in seed funding.
- Cambridge Aerospace raises an estimated £202.3m in a Series C+ round to scale production of its Skyhammer air-defence interceptors for the UK MoD and NATO partners.
- Tresmares provides acquisition financing plus a committed M&A facility to MediMatch, the Queen’s Park Equity-backed UK dental laboratory group, with Santander UK supplying a revolving credit facility.
- Backbone raises €4m for automated food quality and compliance.
- Souk lands $1.6m to turn inactive B2B partners into revenue.
- Pm Links Holdings, a Driffield-based construction holding company, raises an estimated £24.1m.
- Vault Y, a Poole-based holding company incorporated in June, raises an estimated £9.9m.
- Renalytix raises £10.1m in an oversubscribed placing at 6p, clearing its debt to Heights Capital Management in a £13.6m aggregate transaction.
- Nexeon raises £100m in a round backed by the National Wealth Fund.
- The British Business Bank commits up to £46m to Zinc’s new deeptech fund.
- Conveo raises $50m to scale its AI-powered consumer intelligence platform.
- Hammerson prices a seven-year £250m bond issue.
- Octric Semiconductors secures £14m at a £119.4m valuation.
- Ipulse secures £10m for its SmoothSkin technology.
- London AI SEO platform Anvil secures an estimated £8.4m.
- Ki 13 raises $5m for affordable synthetic fuels.


