
 Daniel Black
Ask a room of UK CFOs for their top priority right now and one answer drowns out the rest: cost cuts.
In this issue’s editorial, 68% of CFOs name it as a primary focus, while appetite for acquisitions slips to 16%. But look further down the chart and there’s a line worth circling: 14% now rank selling assets as a priority, up from 9% last quarter.
This week, the sellers showed up. CPP Investments and OMERS agreed to hand most of Associated British Ports to a new owner, Warburg Pincus is selling its Odido stake to Apax, and International Paper is fielding bids for the former DS Smith.
That’s three of the 34 deals in the tracker, and the Rumour Mill is just as lively, from Castore to De Beers.
Thanks for reading, and connect with me on LinkedIn if you want to discuss how I can help with your next M&A deal.
Share your views on data room prices for a chance to win $150
One M&A advisor recently received a €90,000 invoice from his virtual data room provider, nearly four times the original quote. We suspect he’s not alone.
We’re surveying dealmakers across the M&A Community to find out how common hidden VDR costs really are. Share your experience in just two minutes.
As a thank you, everyone who takes part will be entered into a prize draw for a $150 Amazon voucher. All responses are confidential.
Weekly Summary | 23.10.2026
This week we collated 34 UK deals, and energy and infrastructure did the heavy lifting with 11 of them.
The biggest was IFM Investors’ purchase of a 68% stake in Associated British Ports, in a deal reported to value the UK’s largest port operator at around £10bn.
Technology followed with eight deals and healthcare added five, led by Merck KGaA’s $1.3bn move for Silence Therapeutics.
Beyond ABP, energy deals spread across the value chain. Gulf Keystone and ShaMaran agreed an all-share merger valuing ShaMaran at about $601m, and Ember is paying £505m for Aberdeen subsea rental specialist Ashtead Technology. Foresight’s FEIP II fund was busy on the storage side, backing the 1.8GW Earba pumped hydro project in Scotland and buying FRV’s 100MW Nivala battery project in Finland.
More than 20 of the 34 deals crossed a border, and the flow ran both ways. Buyers from Australia, Germany, France and the US came in for UK assets, while UK groups went shopping abroad: PureGym’s £235m swoop on Swiss chain NonStop Gym, The PA’s A$49.8m offer for RAS Technology and Aggreko’s Brazilian power plants among them.
Professional services kept the mid-market ticking, with AAB, Moore Kingston Smith, SLR, LRQA and Seventeen Group all adding bolt-ons.
UK CFOs put cost cuts first, acquisitions later
UK boardrooms are bracing for a tougher year, and acquisitions are slipping down the list.
Deloitte’s latest CFO Survey asked finance chiefs at 66 of the UK’s largest companies about their priorities. It was conducted between 17 September and 1 October, while crude averaged over $100 a barrel. The answer is clear: defence first.
Cost cuts are back on top
Compared with the previous quarter, CFOs have moved away from growth and towards protecting margins:
- 68% rate reducing costs as a strong priority, up from 53% in Q2
- 27% prioritise new products or new markets, down from 37%
- Only 16% rate expanding by acquisition as a strong priority, down from 22%
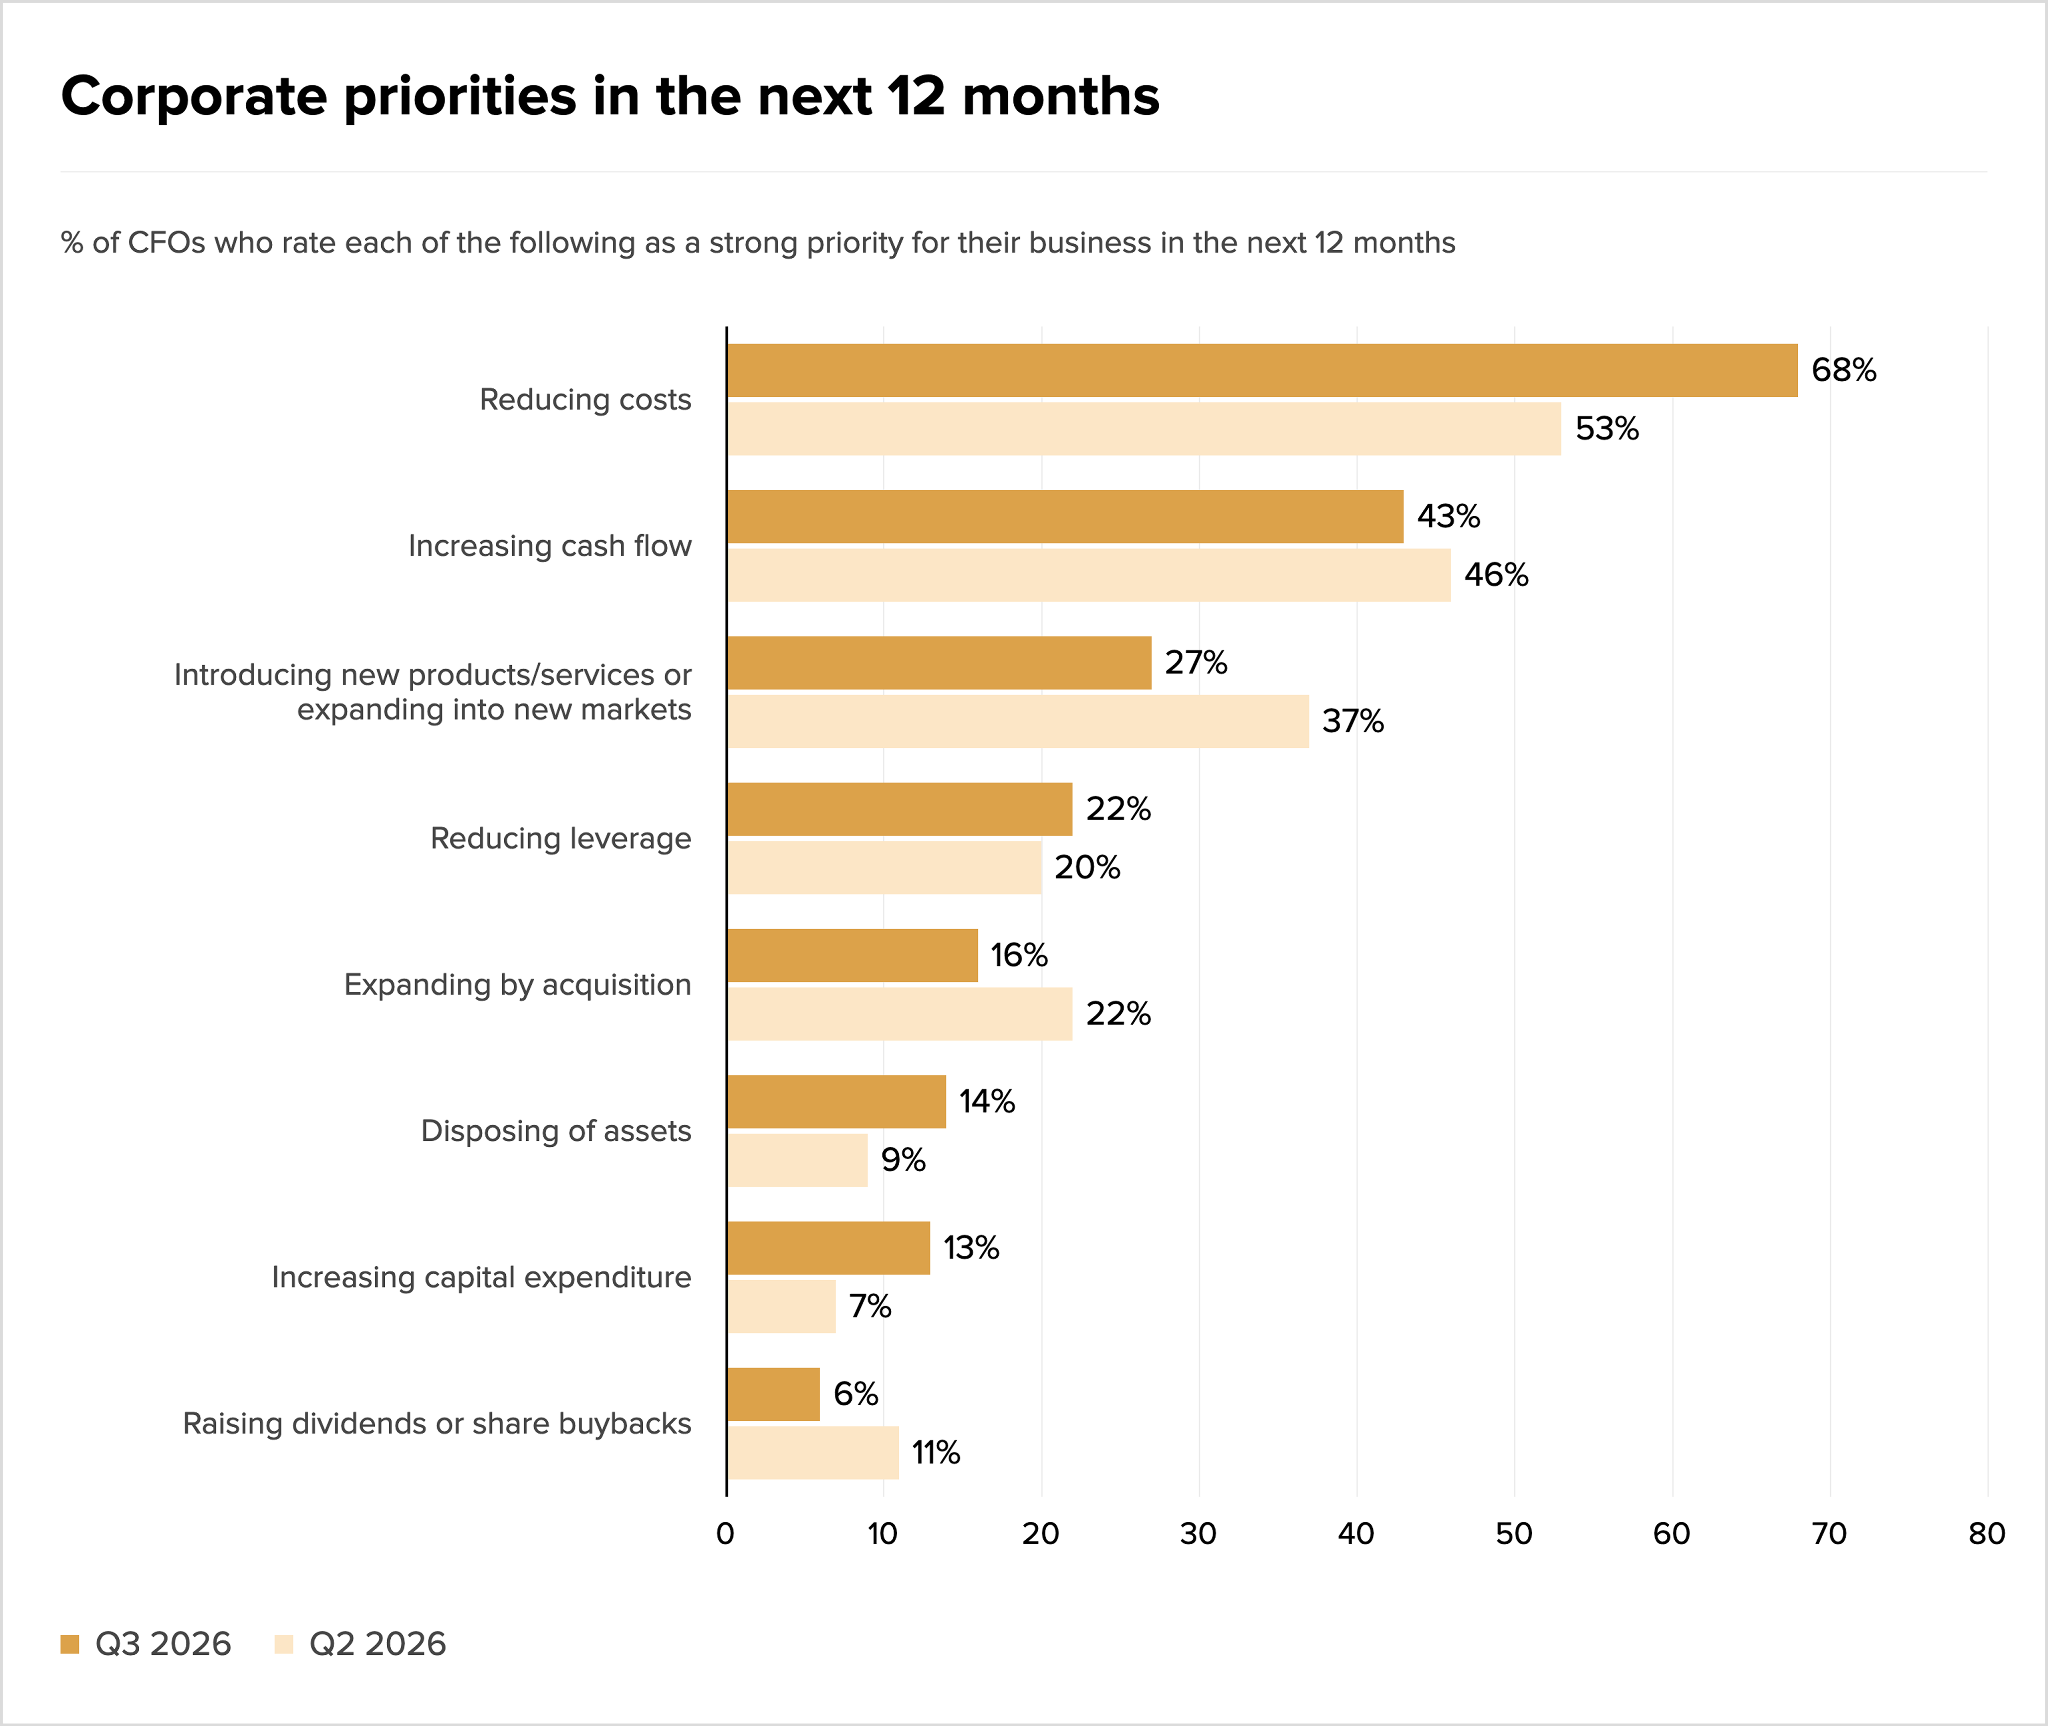
The backdrop explains why. CFOs now expect inflation at 3.4% and Bank Rate at 4% in a year’s time, up from 3.75% today. They rate the cost of credit for their own businesses at a two-and-a-half-year high.
Confidence, not capital
Here is the interesting part. When asked what holds back UK competitiveness, CFOs put domestic economic and political uncertainty first, at 78 out of 100. Cost and availability of finance ranks second from bottom, at just 31.
Deloitte also notes that credit availability remains well above the lows of 2023. The money is there, the conviction to spend it is not.
Look at the smaller bars
Two priorities moved the other way:
- Disposing of assets rose to 14%, from 9%
- Increasing capital expenditure rose to 13%, from 7%
So where does that leave dealmakers? Fewer UK corporates are shopping, but more are pruning. That could mean more carve-outs and non-core disposals reaching the market in the months ahead, just as domestic strategic buyers step back.
The Budget is the next test. If it brings the policy stability CFOs are asking for, acquisition appetite could return quickly. If not, expect sponsors and overseas buyers to keep filling the gap.
Jobs Highlights
Rumour mill
- SThree has extended Circle8’s put-up-or-shut-up deadline to 18 November, giving the US-based bidder more time to firm up a possible all-cash offer for the London-listed recruiter.
- National Express owner Mobico is in talks over a possible 46p-a-share cash offer worth about £282m from Autobuses de León, backed by Spain’s CMC Group and Asterion, which its independent directors are minded to recommend.
- Manchester-based sportswear brand Castore is in talks with Chinese groups Anta Sports and Li Ning over a potential sale as its backers look to exit, the FT reports.
- Canaccord Genuity is in talks to sell its UK wealth arm to Centerbridge and Mubadala for about £1bn, after exclusive talks with Warburg Pincus and CD&R ended.
- B&M is eyeing a small number of Poundland stores as owner Gordon Brothers weighs a sale or break-up of the discount chain, Sky News reports.
- Lone Star and Atlas Holdings are weighing bids valuing International Paper’s European packaging arm, the former DS Smith, at just under $6bn, the FT reports.
- Cartier owner Richemont is in talks to join the Gareth Penny-led consortium bidding for Anglo American’s 85% stake in London-based diamond group De Beers.
- Irenic Capital has built a stake of about 4% in Big Yellow and joined Ancora in pushing the UK self-storage group to explore a sale, the FT reports.
- Barclays cutting 5,000 jobs as it increases reliance on AI
- Shell and Exxon’s $8bn UK chemicals unit put up for sale
Fundraising
- London-based Pantheon has closed its eighth global private equity secondaries fund and related vehicles on $6bn, well above its $3bn target.
- Spanish development finance institution COFIDES has committed €40m to London-based growth investor Bregal Milestone’s third fund through its FOCO co-investment vehicle.
- London-based surgical AI start-up XRlabs has raised $8.4m in a seed round led by Playground Global, with Eka Ventures participating.
- Hg has raised about €1bn at the first close of Orion 1, its debut GP-led secondaries fund, which targets €1.75bn.
- L&G and Dublin-based NTR’s new clean power transition fund has reached a €330m first close.
- Manchester-based insurtech Fruga has raised £1m from NPIF II – PXN Equity Finance and Haatch to scale its open banking tool for cutting insurance renewal costs.
Job moves
- Bishop Fleming has appointed Paul Kurowski as an audit partner in its Birmingham office.
- WTS UK has hired Brad Ashton from RSM as a partner to build its customs and global trade practice.
- Howden has named Enrico Nanni CEO Europe from 1 January 2027, reporting to EMEA CEO Luigi Sturani, while he keeps his role as chief commercial officer for Europe.
- Lazard has hired David Krap from J.P. Morgan as London-based managing director and co-head of European consumer, retail and leisure.
- Cooper Parry has appointed Adam Maitland, who joined through its Hutcheon Mearns acquisition, to lead its national corporate finance business, succeeding Andy Parker.
- Ithaca Energy CEO Luciano Vasques will retire by the end of March, with the FTSE 100 North Sea producer now searching for a successor.
- JD Sports senior independent director Kath Smith will step down from the board on 19 January 2027 after more than seven years.
- Turner & Townsend has appointed Christian Galanis to strengthen its technical due diligence team.
- Tom Windett has joined Opus Strategic Advisory as a partner.
- Maven Capital Partners has opened a Leeds office and hired Greg Allsopp from Venturian as investment director for Yorkshire.
- SDCL Efficiency Income Trust shareholders have approved Saba Capital founder Boaz Weinstein and Devon Equity founder Richard Pavry as non-executive directors, nominated by its two largest investors.
Regulatory
- Liberty Global, Telefónica and InfraVia have rejected the CMA’s interim report on nexfibre’s £2bn Netomnia takeover as “fundamentally flawed” and will not offer remedies, but have not walked away from the deal.
- The CMA is inviting comments until 3 November on Intersurgical’s $530m purchase of Teleflex’s acute care and interventional urology businesses.
- Culture Secretary Lisa Nandy has cleared Axel Springer’s takeover of the Telegraph without a Phase 2 review, ending the public interest process first opened over RedBird IMI’s bid.


