
 Daniel Black
EY publishes its IPO Eye every quarter, tracking what has listed in London and what it raised. The second-quarter edition came out in July, and the headline was encouraging: proceeds up 422% on the same period last year.
The detail is more instructive. Five listings, £564m raised, and one Uzbek fund accounting for £511m of that. Strip it out and the quarter comes to four floats and roughly £53m.
EY also records where each company actually does business. Brazil. Uzbekistan. Tanzania. Botswana. West Africa. Not one of the five has its primary business in the UK.
None of that is a scandal. London has been the natural home for resource listings for decades, and the ecosystem around them works. But it sits oddly next to Deutsche Bank‘s survey of 150 UK-listed directors, published this month, which found 94% expecting IPO volumes to rise and three quarters of them thinking about listing somewhere else. More on both below.
To the deals. Twenty-five in the tracker this week, and three worth your attention:
- Mitie shareholders approved OCS Group‘s £3.1bn cash acquisition, with 94.9% backing the scheme at the court meeting.
- Peel Holdings raised its offer for Harworth to 177.5p, valuing the Rotherham regeneration group at £599.8m. Peel already holds close to 30%, the two sides have not spoken during the offer period, and acceptances close on 25 October.
- Essar‘s EET Retail bought SGN Retail, adding 118 forecourts to its own 117 and creating a 235-site network supplied from its Stanlow refinery.
Thanks for reading, and connect with me on LinkedIn if you want to discuss how I can help with your next M&A deal.
Weekly summary | 18-09-2026
The Deals Tracker logs 25 announced transactions this week, and the largest is not the one with the biggest headline number.
Mitie shareholders approved OCS Group’s £3.1bn cash acquisition on Wednesday, with 94.9% backing the scheme at the court meeting. Completion is expected in the first quarter of 2027, at which point one of Britain’s largest facilities management businesses leaves the London Stock Exchange.
Six items this week involve UK-listed businesses being bought or taken off the board. Beyond Mitie, CyanConnode’s scheme became effective following court sanction, and LondonMetric Property’s did the same.
In the regulatory section, Zurich’s £8.2bn acquisition of Beazley cleared its final conditions, with the court hearing on Monday and Beazley’s listing due to be cancelled on 2 October. And ABB filed its £4.1bn purchase of Rotork with the Austrian authority, another FTSE 250 name on its way out at 503p a share.
Two are still being fought. Peel Holdings raised its offer for Harworth to 177.5p, valuing the Rotherham regeneration group at £599.8m. Peel already holds close to 30%, there has been no engagement between the parties, and acceptances close on 25 October.
Elsewhere the week was mid-market. RSK bought twice, taking Australian renewables consultancy Cogency and highways specialist MSF. Bondcare paid £9.1m for a care home in Ilford, Crossbay took a 325,000 sq ft logistics portfolio, and Debenhams Group sold its Sheffield distribution centre for £90m.
London’s recovery quarter had no British issuers
EY published its IPO Eye for the second quarter in July, and the headline number is a cheerful one. Five listings on the London Stock Exchange, £564m raised between them, a 422% increase on the same quarter a year earlier.
It is worth looking at where that money came from before we get too pleased with ourselves.
UzNIF JSC, an Uzbek fund, accounted for £511m of the £564m. That is 91% of the quarter in a single admission. Take it out and Q2 comes to four floats raising roughly £53m, which is less a recovery than a rounding error.
Then read the country column. Brazil, Uzbekistan, Tanzania, Botswana, West Africa. Not one of the five companies admitted to London in the second quarter has its primary business in the UK. Three are mining or oil and gas, two are funds, and the private-equity-backed column is empty for all five.
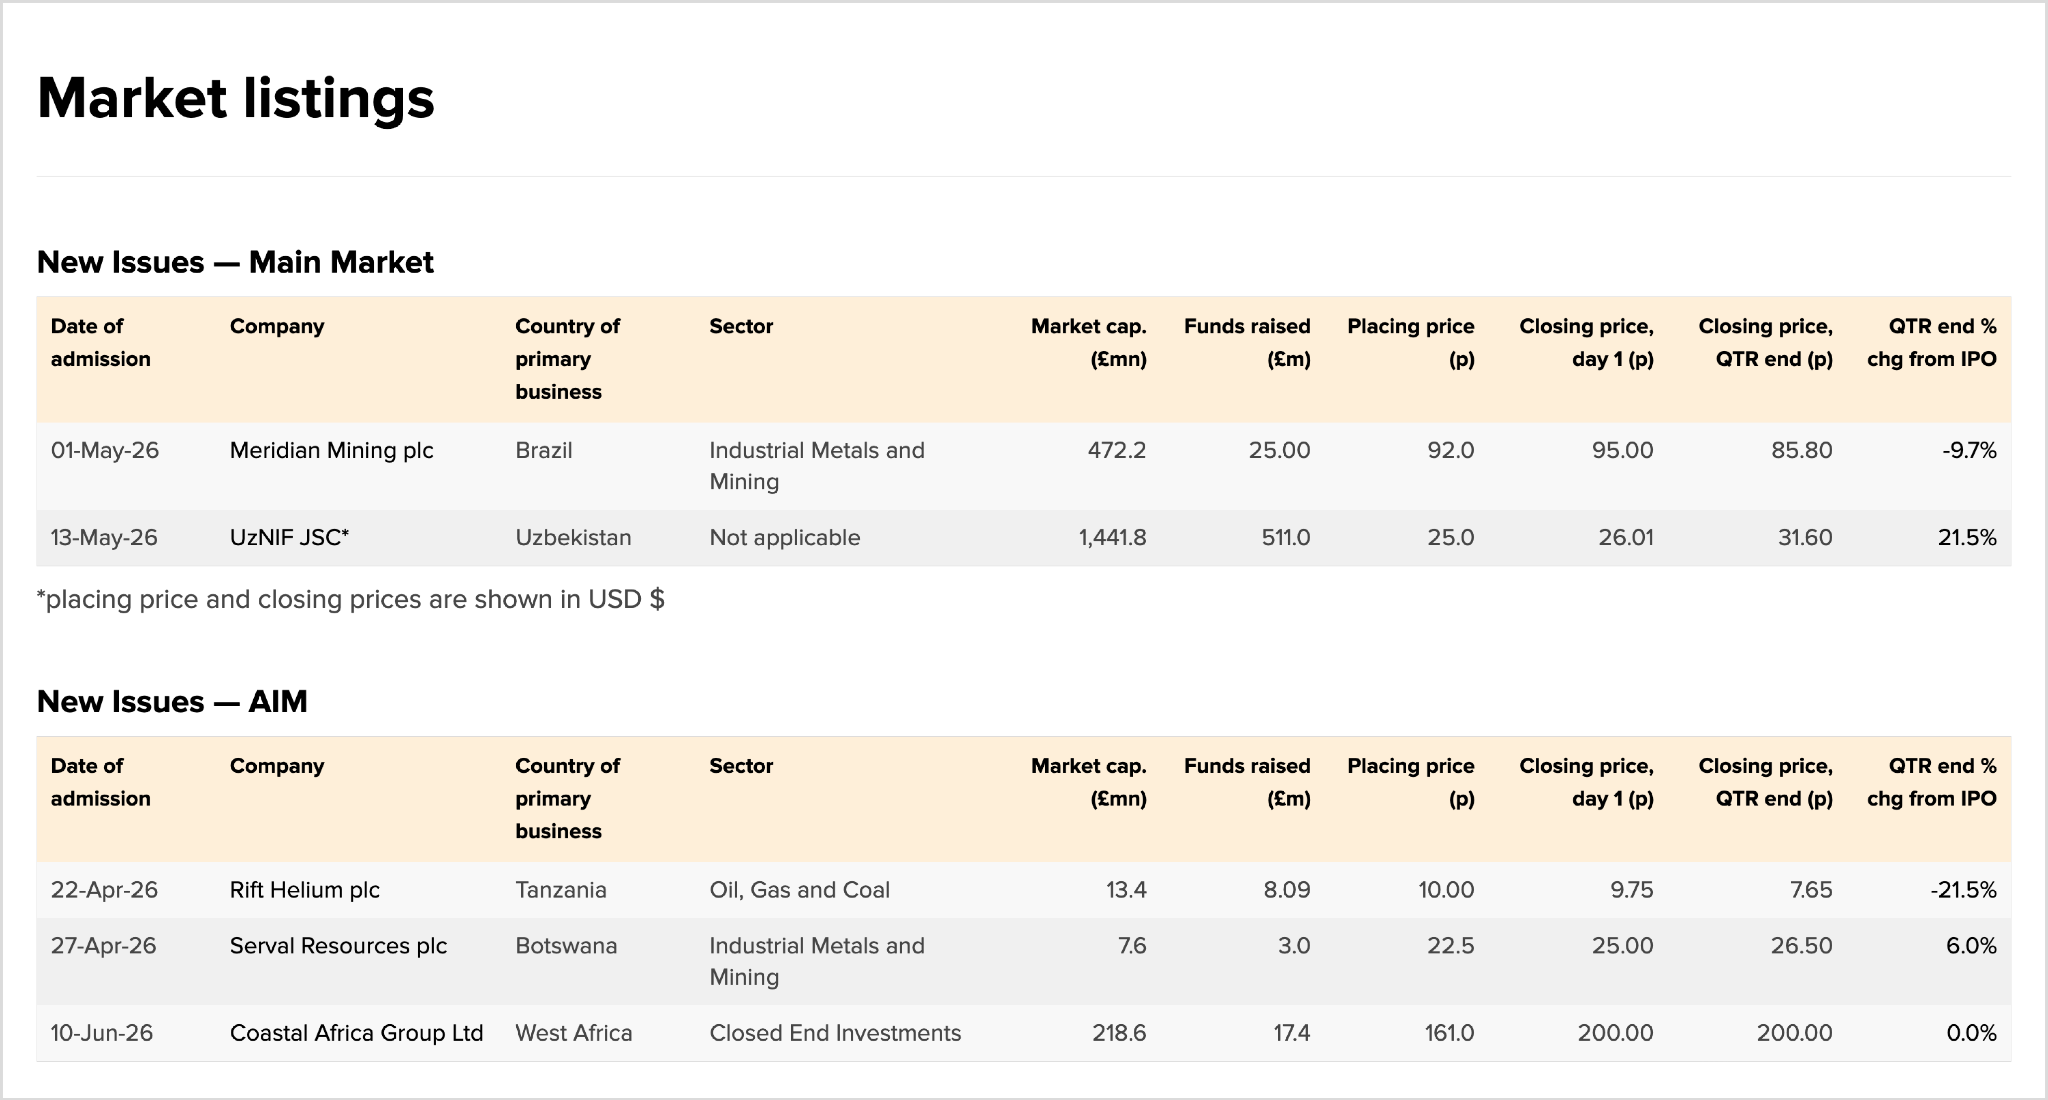
None of which is odd in itself. London has been the natural home for resource listings for decades, with the nomads, the specialist brokers and the institutions to match, and it remains a serious venue for closed-end funds. A company with assets in Tanzania incorporates an English plc, lists here, and gets English law and sterling investors. That part of the market is working exactly as designed.
It is everything else that has gone quiet. Which is awkward, because Deutsche Bank surveyed 150 UK-listed directors in July, in the weeks immediately after that quarter closed, and found 94% expecting UK IPO volumes to rise over the next two years. 
To its credit, Deutsche Bank says the quiet part out loud: the perceptions have not yet translated into a material uptick in ECM volumes, and unlike other global exchanges, the pipeline has yet to produce a run of completed transactions.
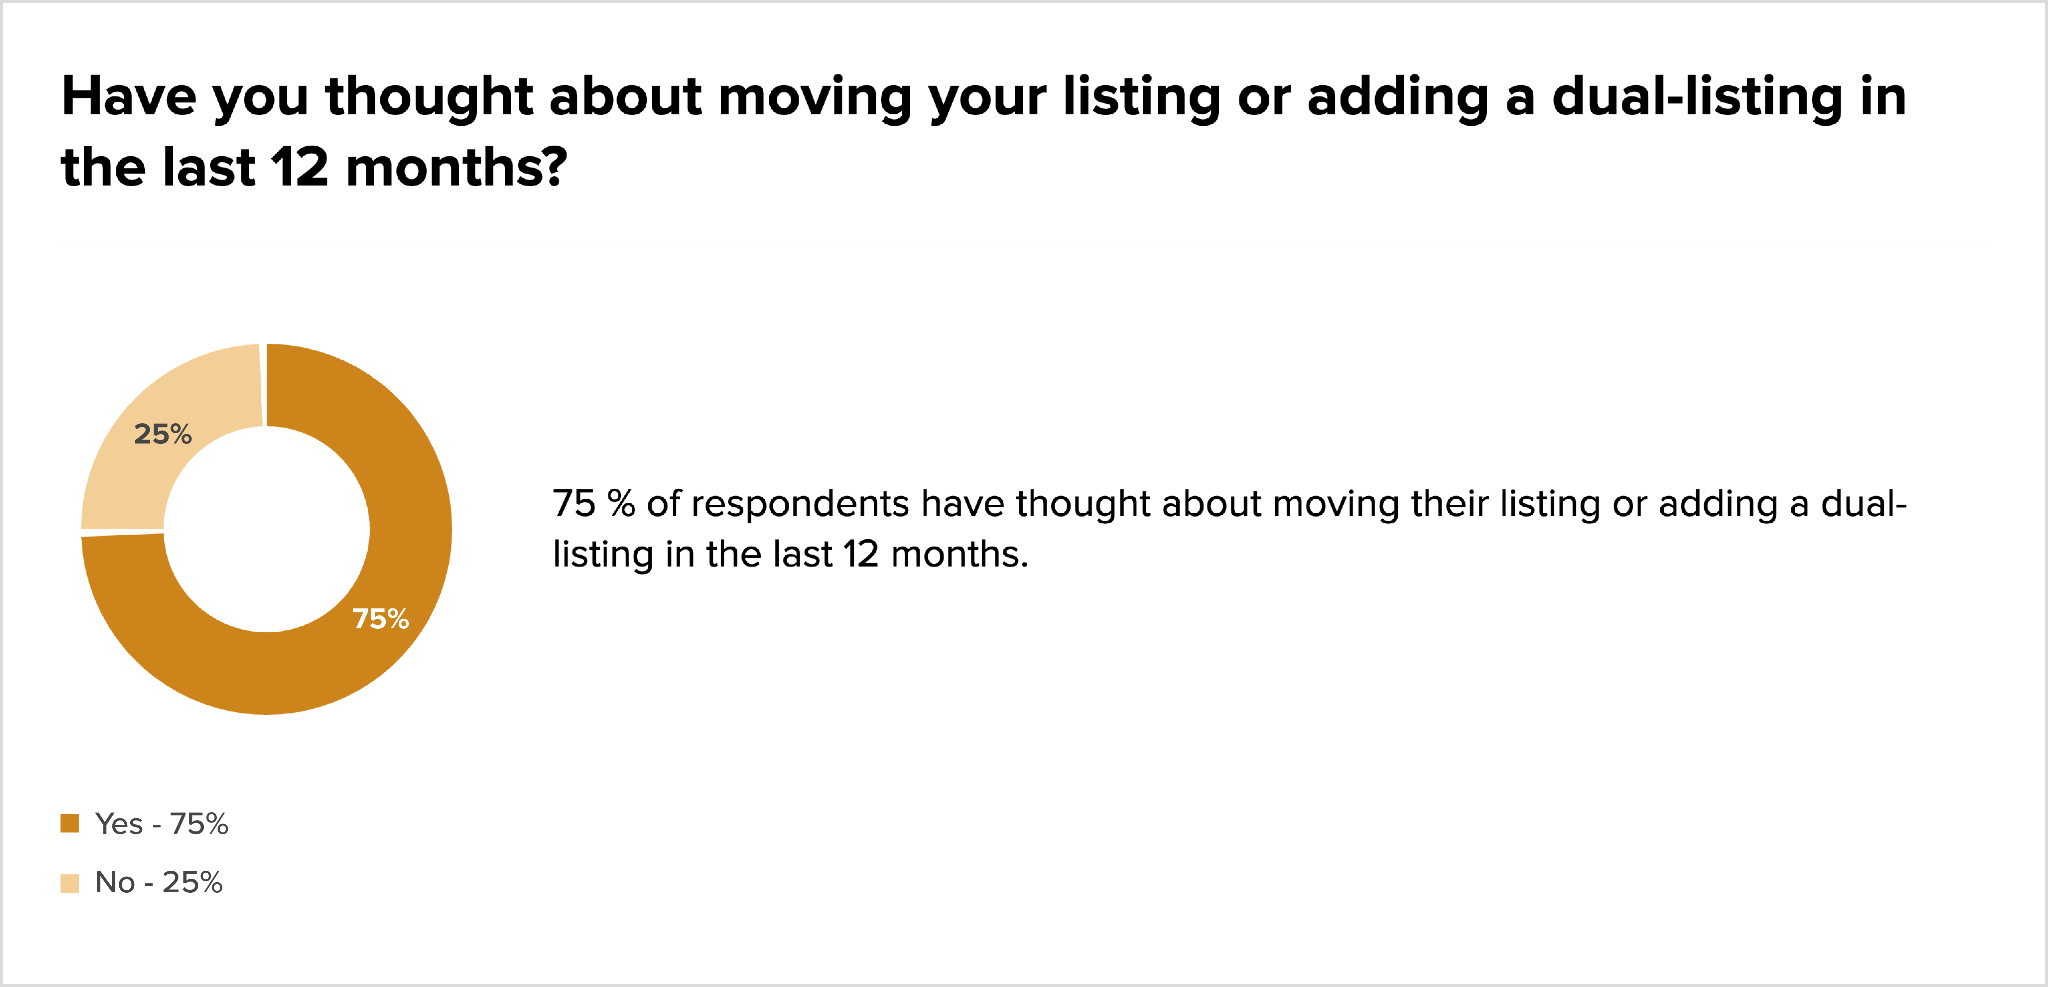
The other finding is harder to shrug off. Three quarters of those same directors have considered moving their listing or adding one elsewhere in the past twelve months, with 73% looking at New York and 62% at Amsterdam. It is down from 83% last year, which is something.
This week gave us both halves again. Utmost Group is weighing a £2.5bn London float and D’Ieteren is exploring a listing for Belron, while Dusk quietly shelved its £300m one.
What to watch: whether EY’s Q3 table, due next month, contains a single British operating company.
Rumour mill
- Aberdeen’s Union Square shopping centre is placed on the market for £175m.
- Accel-KKR makes a recommended cash offer for construction software group Eleco.
- Peel Holdings raises its cash offer for Harworth Group to 177.5p a share, valuing the Rotherham regeneration group at £599.8m. Acceptances close on 25 October.
- System1 rejects Brave Bison’s increased fourth offer, made two days earlier.
- A key Derby regeneration site comes to market following the collapse of its developer.
- Schroders is weighing acquisitions to expand its wealth management division.
- Vista Equity Partners is exploring strategic options for Finastra, the London-headquartered financial software provider.
- The UK government is seeking to acquire an insolvent specialist steelmaker.
- Eagle holds first talks with Thames Water’s leadership as the bailout crisis continues.
- Scottish SPFL club Spartans teams up with former USA goalkeeper Brad Friedel in a bid for Shrewsbury Town.
- A man pleads guilty to fraud and forgery offences relating to a fake takeover approach, following an FCA prosecution.
Regulatory
- The CMA commences its merger inquiry into McCormick & Company’s anticipated acquisition of the majority of Unilever’s foods business.
- ABB files its £4.1bn acquisition of Bath-based flow control group Rotork with the Austrian competition authority. The recommended cash offer, at 503p a share, is ABB’s largest ever deal.
- Zurich’s £8.2bn all-cash offer for Beazley clears its remaining regulatory conditions. The court hearing is set for 22 September, with the scheme expected to become effective on 1 October and Beazley’s London listing cancelled the following day.
- Merger update on Welltower’s acquisition of multiple care homes.
- Beowulf Mining updates on its £4.3m financing and the foreign direct investment approval process.
- The Department for Business, Innovation, Science and Trade refers its proposed Critical Chemicals Resilience Fund subsidy scheme to the CMA.
- Ørsted receives a final opinion on the taxation of its Walney Extension and Hornsea 1 offshore wind farms.
Job moves
- A team of four data centre specialists moves to Astor, bringing a €5bn development pipeline.
- Aberdeen Football Club appoints Adrian Bevington as chief executive.
- Cameron Pearce moves from the board of Gledhow Investments to a non-board strategic adviser role.
- Affinity Water Finance announces a directorate change.
- Caledonia Investments appoints a non-executive director.
- Elementis appoints a senior independent director.
- Proteome Sciences appoints a non-executive director.
- Invesco’s Asia veteran Ian Hargreaves is to retire next year.
- Fresnillo announces a planned CFO succession.
- Sound Point Capital appoints Victoria Davies as managing director and head of Europe for global client solutions.
- Avacta appoints Mats Blom to its board as chair of the audit committee.
- Alan Lovell is appointed chair of British Steel.
- The chief executive of Safe and Sound retires after seven years.
- A Wachtell, Lipton, Rosen & Katz dealmaker moves to Linklaters as the firm expands in the US.
- Alison Kay is appointed chair of the Regen board.
- HSBC announces a group CFO succession.
- James Lowe, UK wealth director for private markets at Schroders Capital, departs the firm.
- DTZ Investors appoints Nicholas Garattini to the newly created role of head of capital formation.
- John Mulqueen is to leave his role as chief investment officer at Canary Wharf Group.
- Downing strengthens its private credit offering with a senior hire.
IPOs
Fundraising
- ETFBOOK raises $13m to expand its ETF data intelligence layer into the Americas and Asia Pacific.
- EZO reaches financial close on a €150m senior debt facility.
- HSBC Asset Management launches a sterling short-duration bond fund.
- The Observer raises £10m to fund its restructuring plan.
- Aterian’s Eastinco raises funds to trial tungsten trading.
- Empyrean Energy completes its equity capital raising.
- Keyridge Asset Management is to launch a Systematic Core Global Equity Fund.
- Open Cosmos raises €300m to expand its satellite constellation and deliver real-time intelligence and connectivity from space.
- A group of UK banks begins raising capital for a venture intended to create a new national payments provider.
- Constantine closes a £100m loan to finance a UK battery storage portfolio.
- Starlight Investments announces the successful close of its UK build-to-rent Fund II.
- Sage Group’s €500m bond is admitted to trading.
- South East Water abandons a planned bond issue as investors retreat from the water sector.


