
 Daniel Black
A month ago, fund managers were at their most confident since January.
According to S&P Global’s latest Investment Manager Index, their risk appetite fell in September to its lowest level since March. Half now expect US equities to lose value over the next 30 days, and 63% expect the Fed to raise rates this year rather than cut them.
It also notes a marked difference between sectors. Energy investors remain bullish, while real estate is the least favoured by some distance. Our editorial looks at what drove the change and what it could mean for deal activity.
For now, UK dealmaking is holding up. Three deals stood out this week:
- Softcat agreed to acquire US IT solutions provider GDT for $1,050m (£785m), funded partly by a £350m placing. CEO Graham Charlton described it as a significant step for the group’s US capability.
- DNO revised its $396m offer for Capricorn Energy to an all-cash structure at $5.214 per share. Capricorn’s board will recommend it, about 10% above Genel‘s earlier offer.
- Zurich‘s takeover of Beazley received court sanction this week. Beazley shares are expected to be delisted on 2 October.
Thanks for reading, and connect with me on LinkedIn if you want to discuss how I can help with your next M&A deal.
Have you ever been surprised by a VDR bill?
One M&A advisor recently received a €90,000 invoice from his virtual data room provider, nearly four times the original quote. We suspect he’s not alone.
We’re surveying dealmakers across the M&A Community to find out how common hidden VDR costs really are. Share your experience in just two minutes.
As a thank you, everyone who takes part will be entered into a prize draw for a $150 Amazon voucher. All responses are confidential.
Weekly summary | 25-09-2026
This week we tracked 21 transactions in the UK: 13 M&A deals and 8 fundraisings. Property was among the busiest sectors, with seven deals, a striking contrast with fund managers’ gloomy view of real estate.
The biggest ticket was tech. Softcat agreed to buy US IT solutions provider GDT for $1,050m (£785m), part-funded by a £350m placing. It’s a bold bet on the US market at a time when many buyers are holding back.
Takeover battles moved on. DNO switched its $396m offer for Capricorn Energy to all cash, and Capricorn’s board will back it. Peel’s bid for Harworth became a mandatory offer at 177.5p after its stake reached 30%. And the court signed off Zurich’s takeover of Beazley, with delisting expected on 2 October.
Property kept moving, despite the headwinds. Daiwa House is taking a significant minority stake in Miller Homes from Apollo, Tritax bought London logistics assets for more than £130m, and Cheyne Capital provided a £121m loan for the refurbishment of 1 Poultry.
On the capital markets side, the signals were mixed. RAC shelved its London float in favour of a continuation vehicle. Yet Revolut is weighing a dual listing in New York and London, and cinema chain Vue is exploring a London IPO.
All this against a tough global backdrop. Preliminary LSEG data shows global M&A volume down 49% in Q3 on the previous quarter. The UK’s week suggests mid-sized deals are still getting done, even as megadeals dry up.
Fund managers lose their nerve in September
In August, fund managers were in their most confident mood since January. A month later, that confidence had gone.
S&P Global’s latest Investment Manager Index, which surveys around 300 institutional investors, shows risk appetite falling to its lowest level since March. Half of respondents now expect US equities to lose value over the next 30 days. Only 21% expect gains.
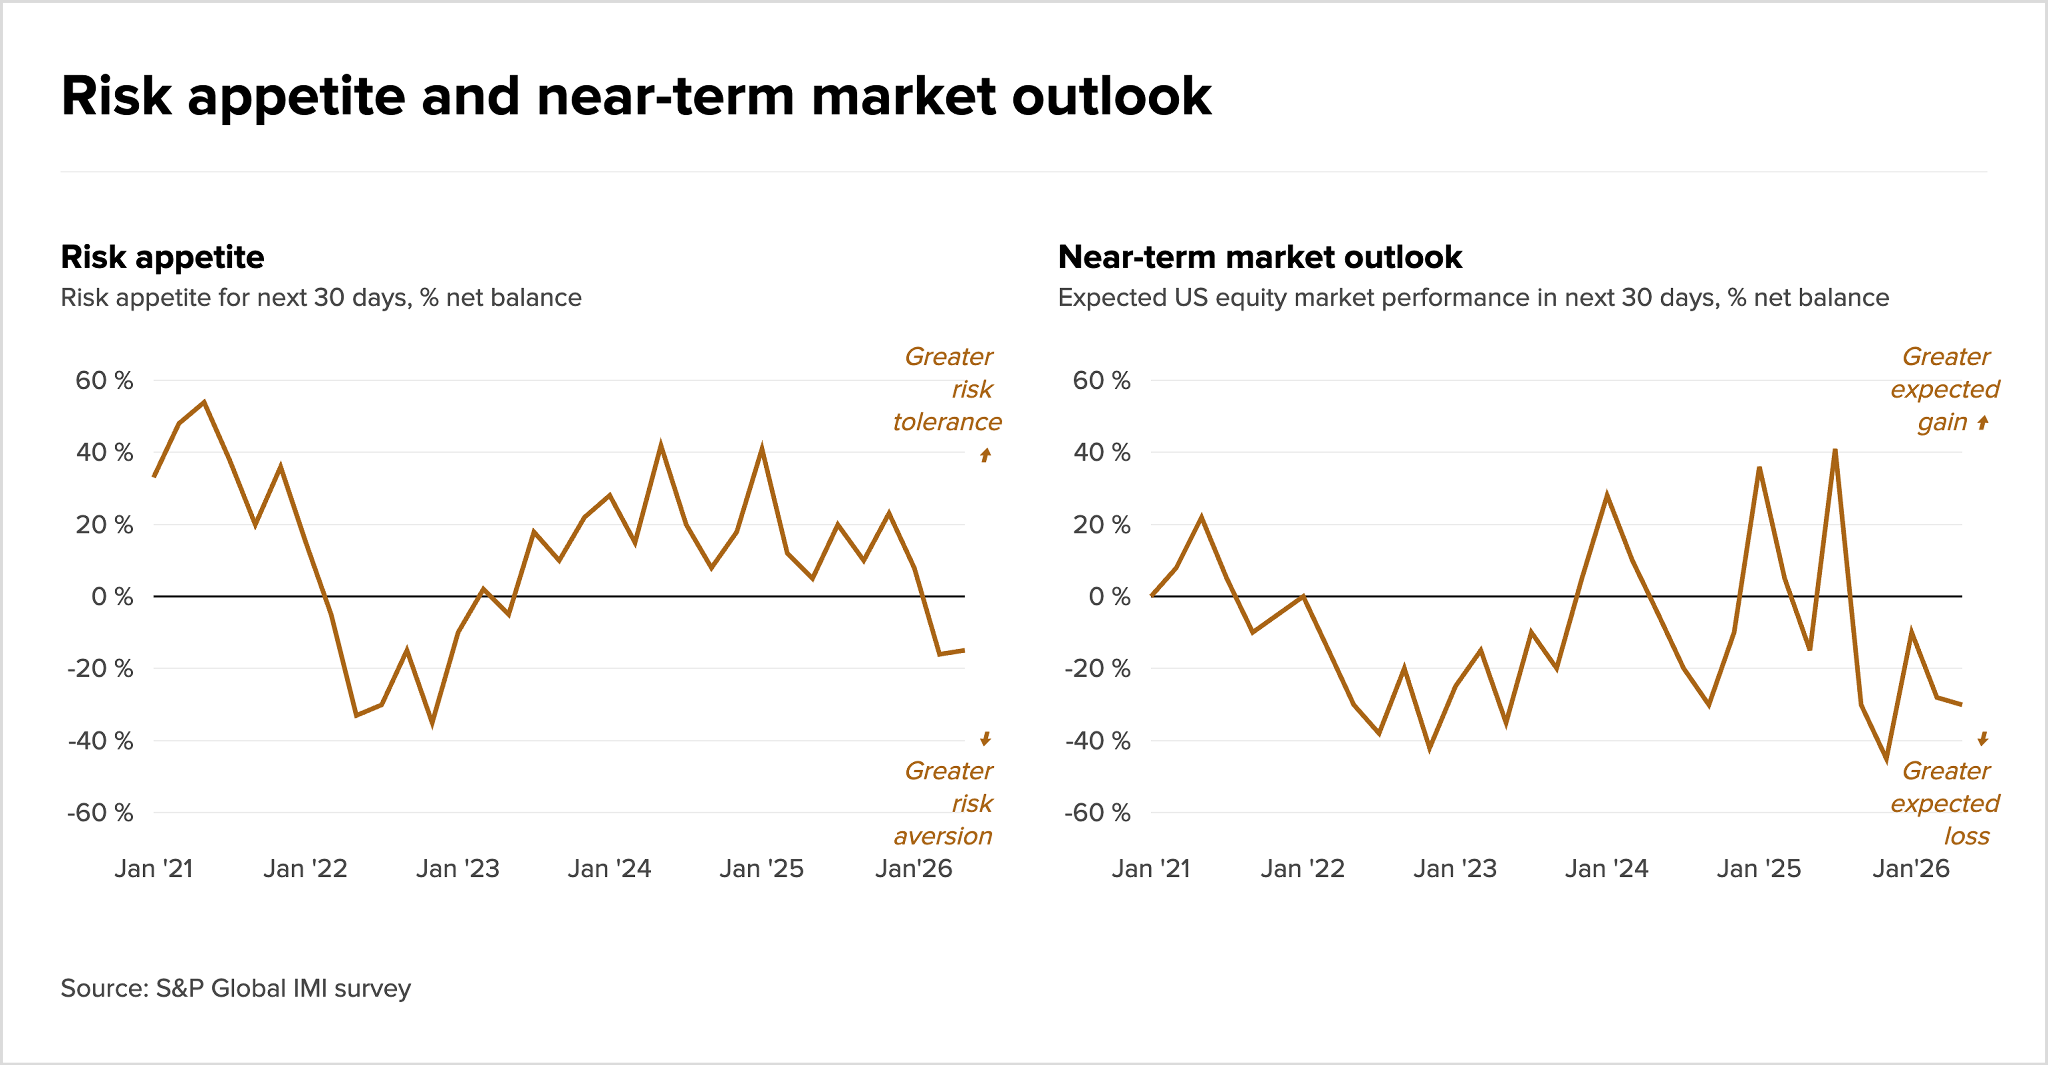
What changed? Two things, more or less at once:
- The Middle East. Renewed conflict broke out while the survey was in the field, between 3 and 10 September. By 21 September, most Gulf markets were still in the red.
- The Fed. In March, most managers expected rate cuts. Now 63% expect the Fed to raise rates by up to 50 basis points this year. Just 3% expect cuts.
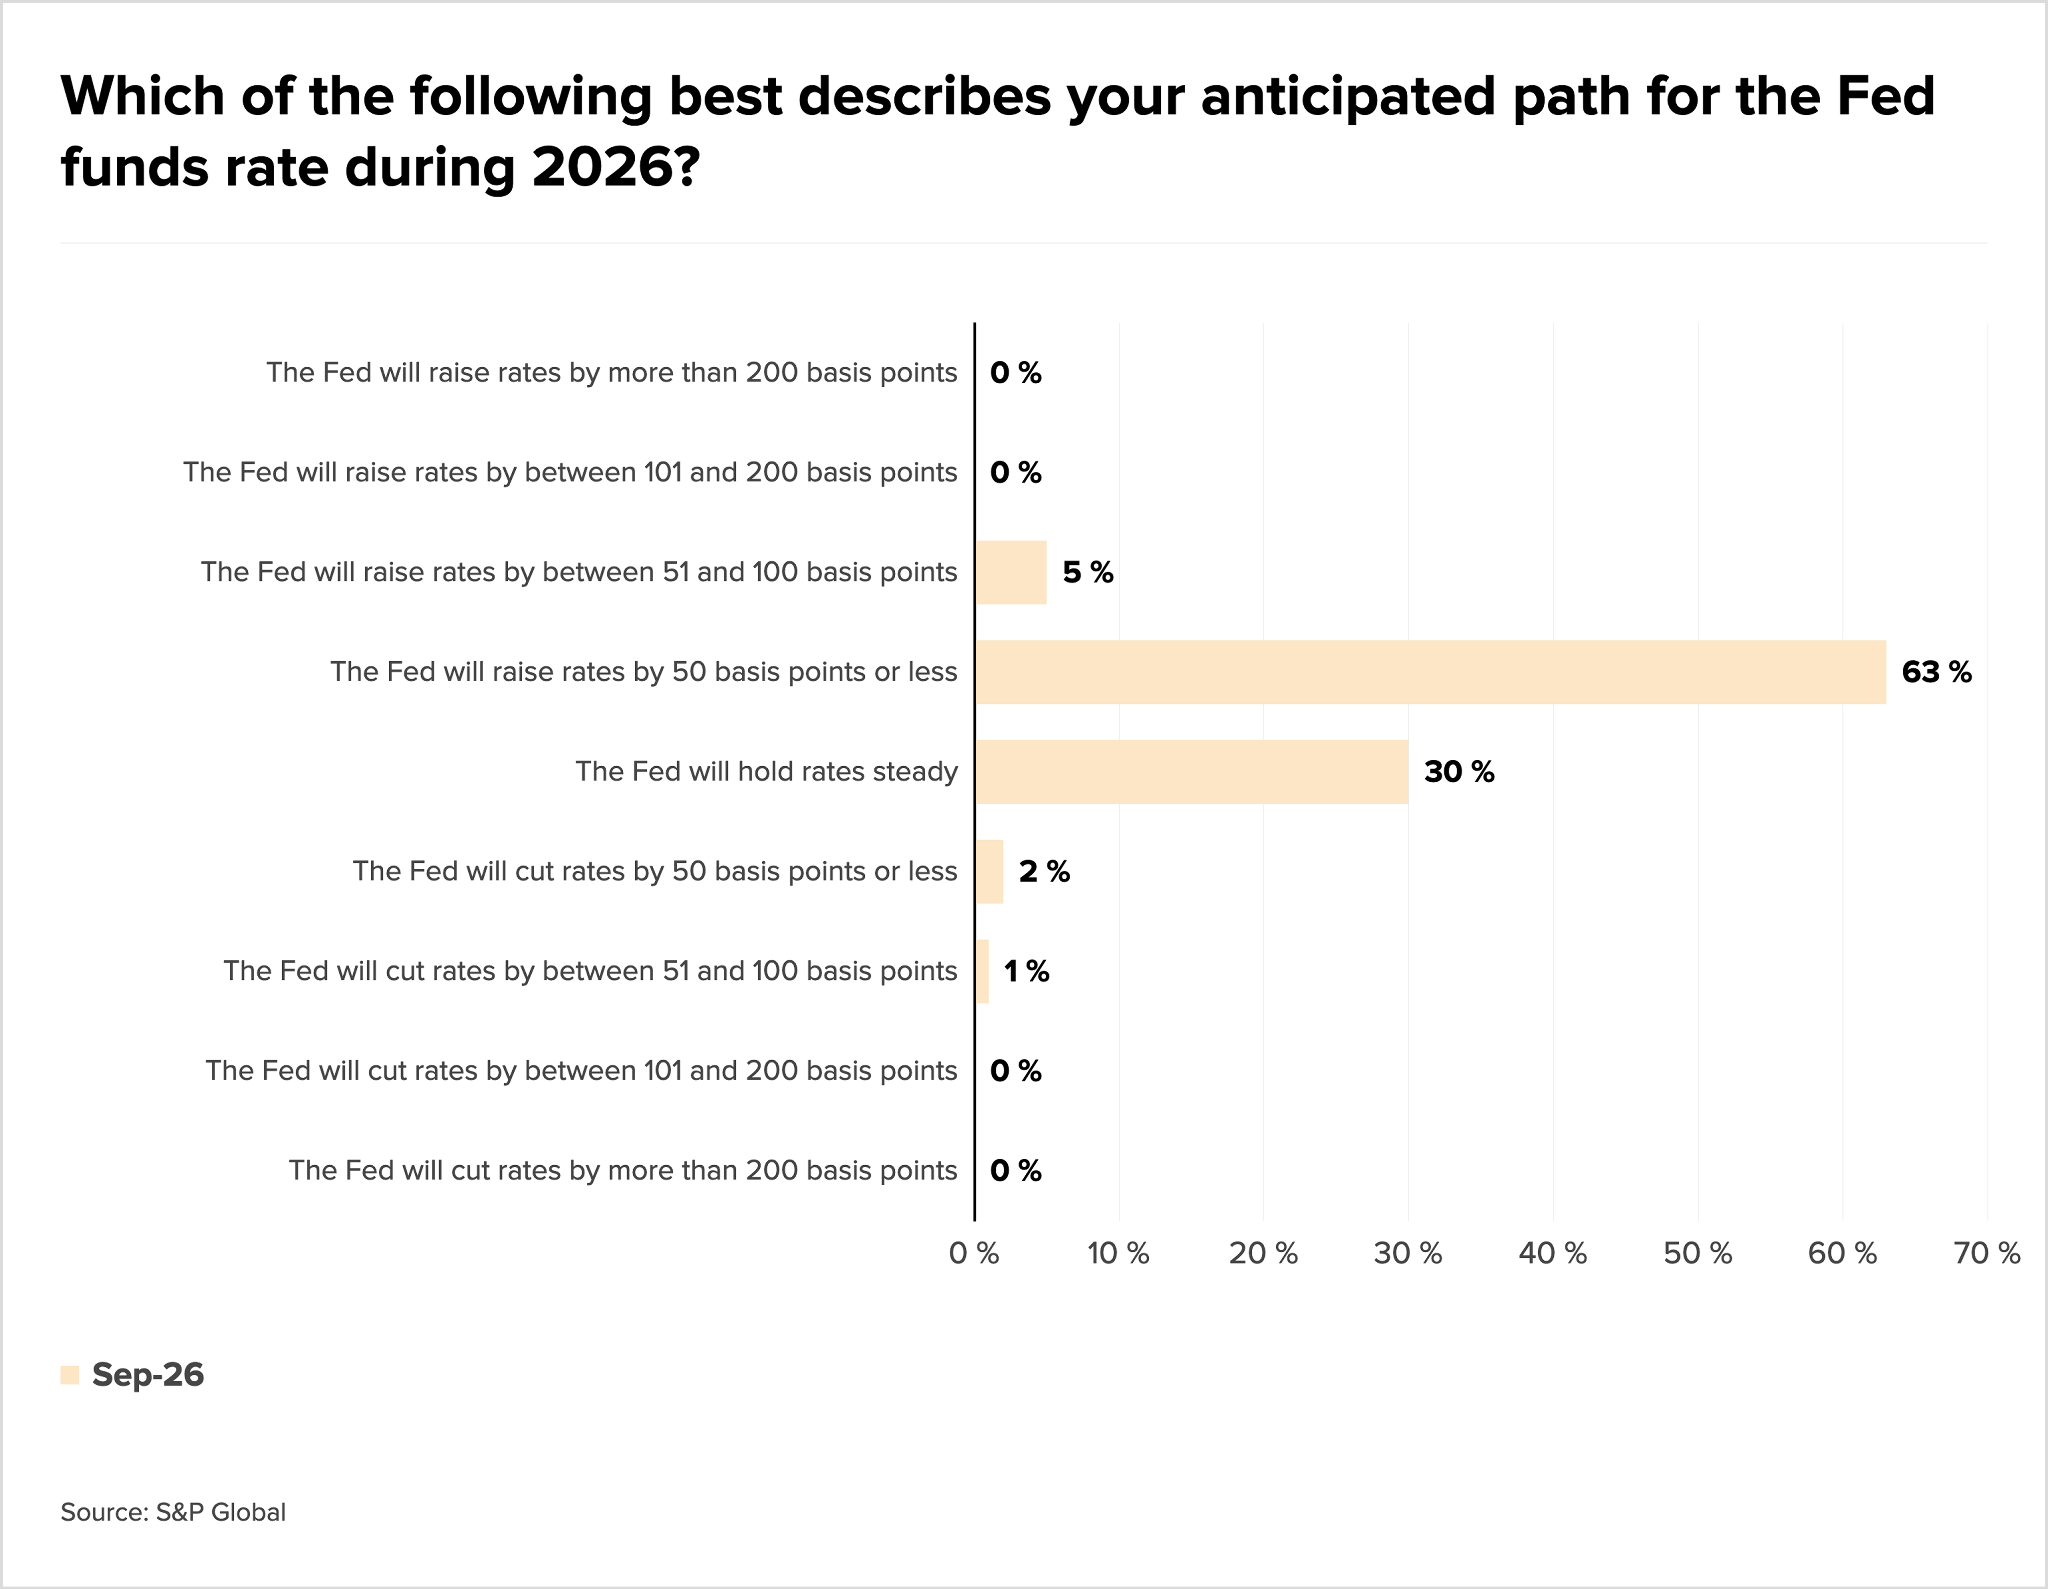
Where the money is heading
Sector views have split sharply. Energy is the clear favourite, with a net 49% of managers bullish. Real estate sits at the other end, at minus 51%. Higher rates for longer are unwelcome news for anything that relies on cheap financing.
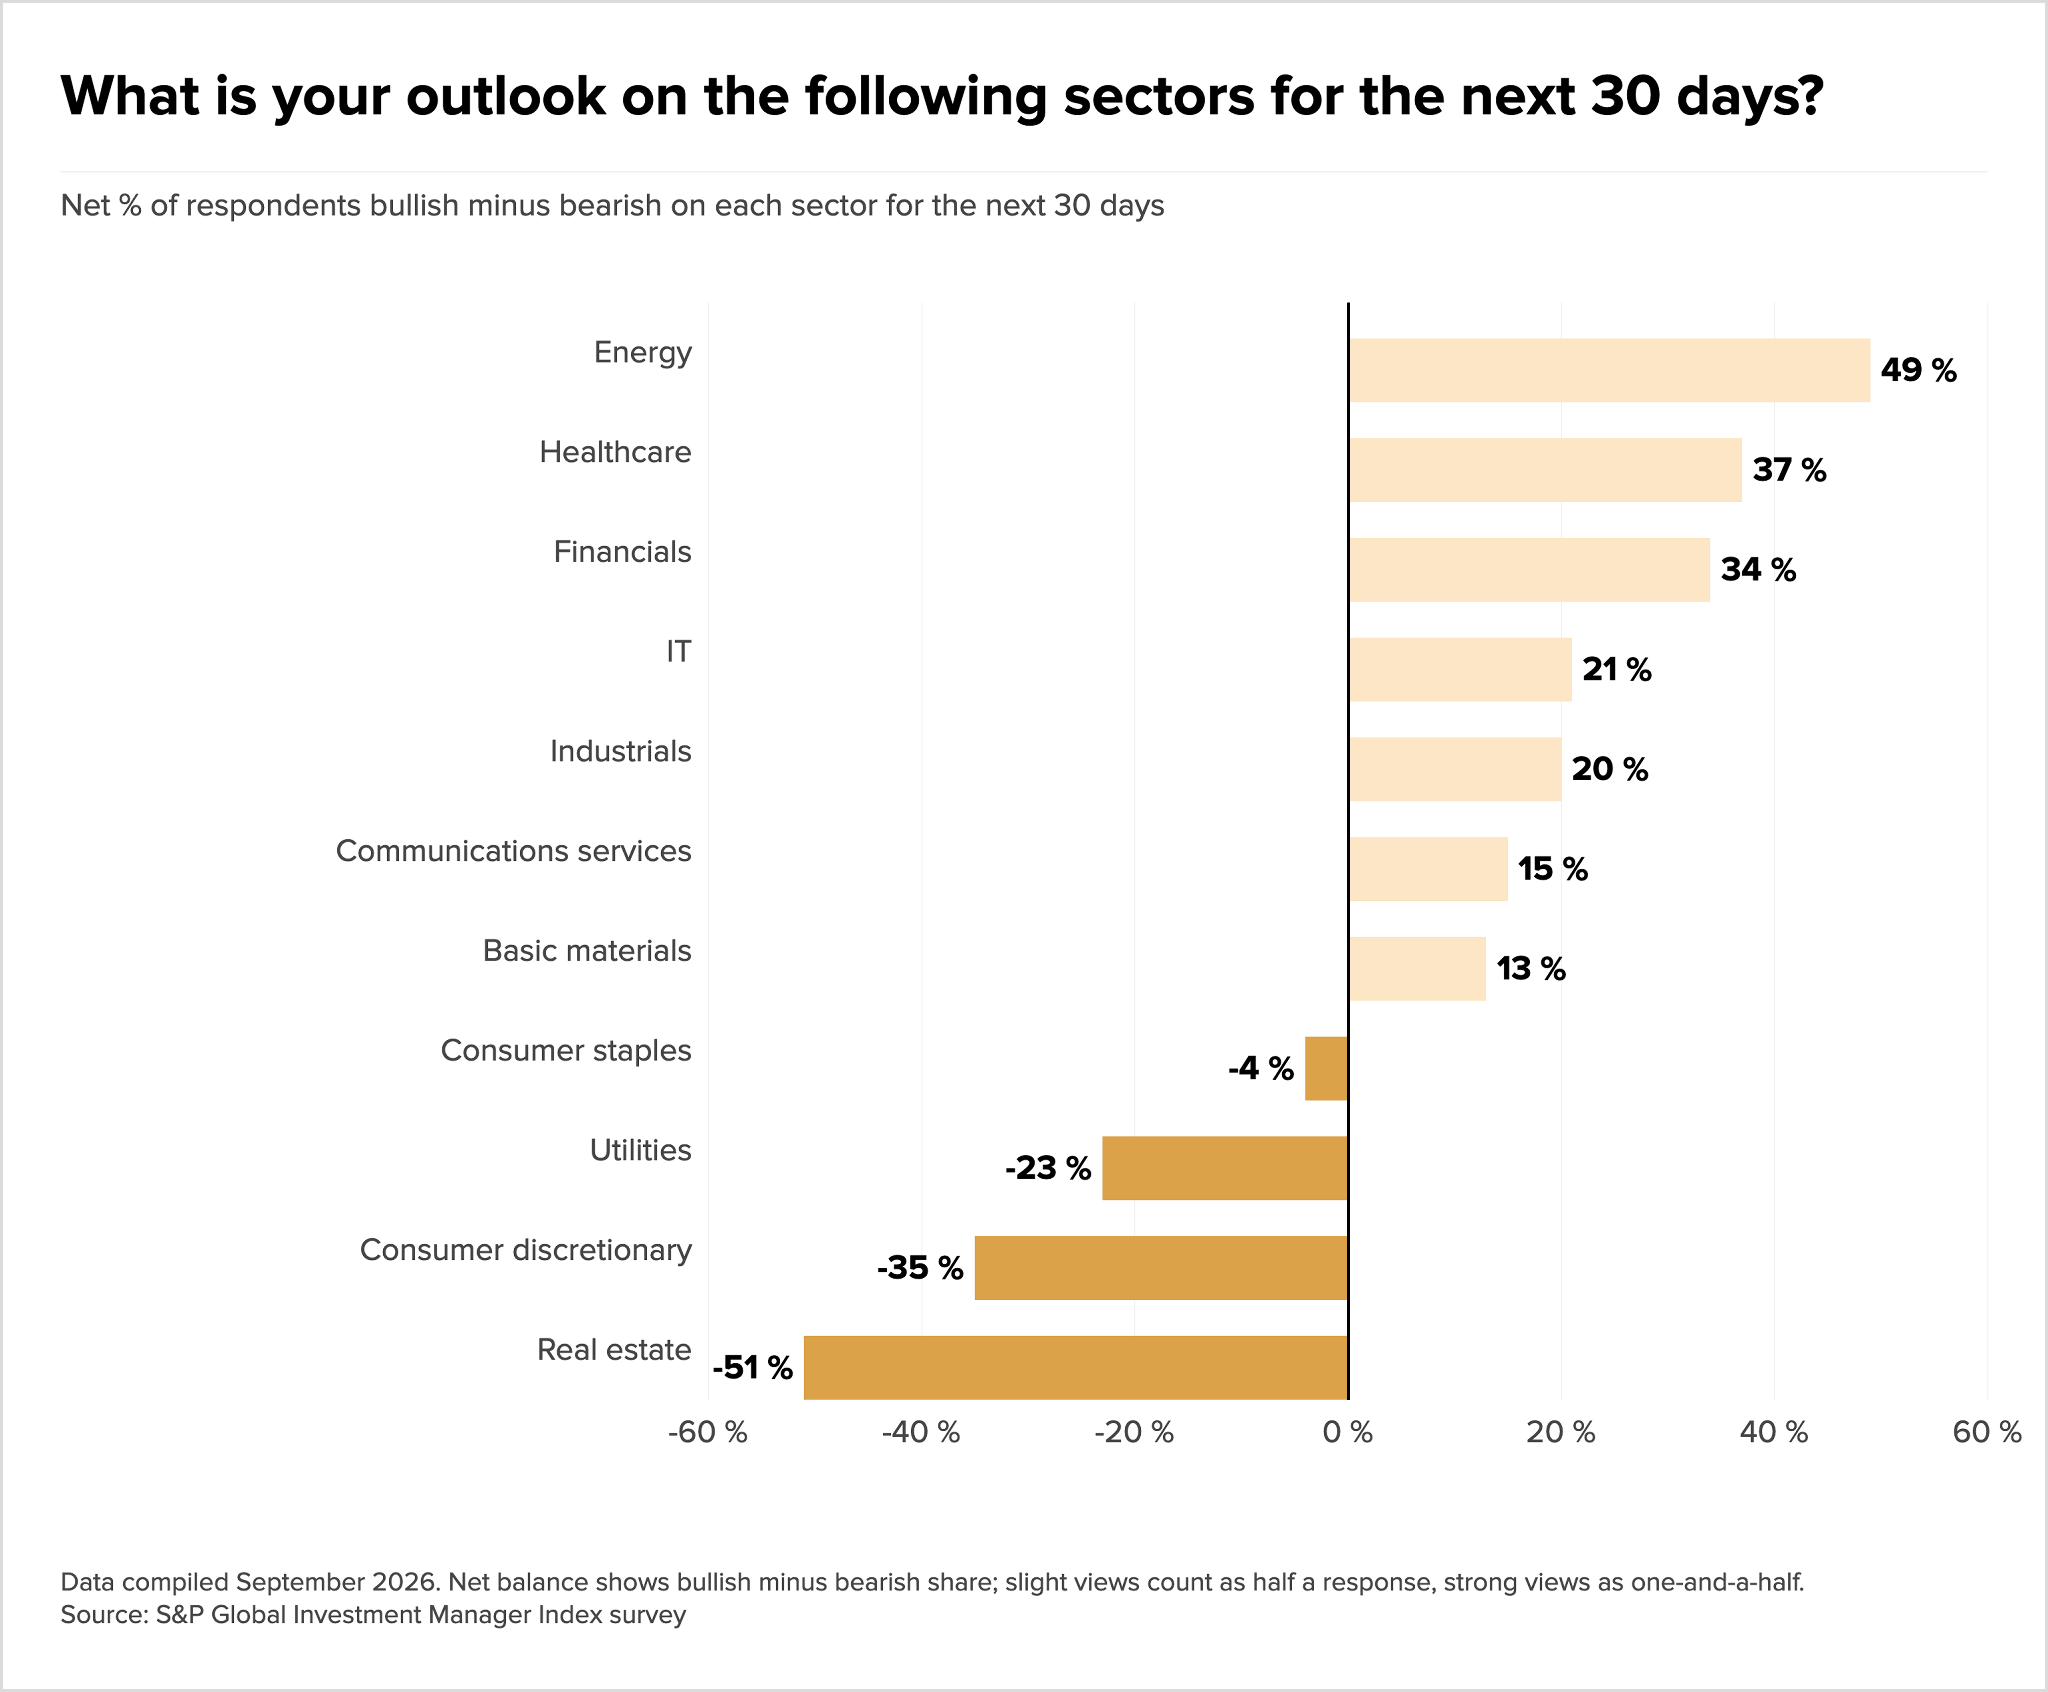
Why it matters for dealmakers
The mood could already be showing up in the numbers. Preliminary LSEG data puts global M&A volume in Q3 down 49% on the previous quarter, with deal count down 39%. Megadeals have all but disappeared: nine deals of $10bn or more so far this quarter, against 27 in Q2.
None of this means the market has shut. But with buyers rethinking their models, the deals that get done are likely to be the ones that still work if rates go up, not just if they come down.
Rumour mill
- CD&R and Warburg Pincus reportedly team up on a joint bid for Canaccord Wealth.
- TalkTalk steps up efforts to secure its future as its deal with Octopus stalls.
- Revolut weighs a dual listing in New York and London for its long-awaited IPO.
- Cinema chain Vue explores a London listing after a bumper summer.
- A month-old DeepMind spinout nears a $4bn valuation.
- Quadient announces intention to sell Lockers business. As a first step, sale of UK open network signed for €65 million.
- Frasers Group extends the offer period for its Accent Group bid to January 2027.
- Does Airtel Money mark the end of London’s listing drought? Not yet
Regulatory
Job moves
- Football financier Amanda Staveley joins the board of tokenisation start-up Ctrl Alt.
- Reward promotes Enrique Del Rio to UK and European president.
- Portmeirion Group announces a directorate change.
- hVIVO announces board changes.
- Record plc announces a directorate change.
- TP ICAP announces a directorate change.
- The Mission Group announces its chair succession.
- Schroders names Westerman as chair ahead of the close of its deal with Nuveen, and updates on the conditions timetable.
- Goldman Sachs appoints Simon Lyons as co-head of UK investment banking.
- CBRE further strengthens its debt and structured finance team.
- Hamilton Lane appoints Diana Celotto to its London investment team as its European presence grows.
- Foresight Technology VCT announces board changes.
- Crism Therapeutics appoints a non-executive chair.
- Foresight Environmental Infrastructure appoints an independent non-executive director.
- RWS appoints former Bytes Technology chair Patrick De Smedt as chair from 8 October.
- Savills appoints a new non-executive director.
- David Avery-Gee and Sarah Flaherty join Sullivan & Cromwell’s London office to strengthen its M&A practice.
- NBPE Announces Appointment of New Non-Executive Director and Chairman Designate
- Lift Therapeutics Appoints Daniel Passeri as Chief Executive Officer
- Former Google EMEA Travel Leader Joins OAG Board as Non-Executive Director
- Diageo appoints WPP’s Joanne Wilson as new finance chief
- Drastic Dave’ hires ex-Tesco colleague to accelerate Diageo turnaround
IPOs
Fundraising
- Stonepeak announces an investment in AMPYR Distributed Energy.
- Savannah Energy announces a proposed fundraise.
- FintechOS secures $28m in combined equity and debt financing.
- A new solo GP firm backing early-stage AI and deeptech start-ups hits the first close of its maiden fund.
- Payments company Ryft lands a £20m Series B to fund its expansion into the EU and US.
- Nationwide Building Society publishes final terms for a new issue of core capital deferred shares.
- Victoria plc gives a trading update and an update on its refinancing transaction.
- Brookfield agrees to invest up to $600m in ACME’s green fuels business in India.


