
 Daniel Black
Coca-Cola is again weighing a sale of Costa Coffee, months after shelving its first attempt amid weak private equity interest.
It’s the clearest sign yet of a broader shake-up hitting the UK high street. Buyout firms are reportedly lining up exits from PizzaExpress, Itsu, Waterstones and Third Space too, as UK consumer dealmaking picks up, per Private Equity Wire.
We can also add self-storage group Big Yellow to that list, with reports suggesting that activist investor Ancora is pushing for a sale after takeover talks with Blackstone collapsed last year.
Elsewhere, Bloomberg reports that Everton’s owner The Friedkin Group is reportedly weighing a sale of its controlling stake in the football club, less than two years after buying it.
Looking at confirmed activity, the Deal Tracker features 36 transactions this week, including:
- DCC agreed to sell its technology division Nexora to One Equity Partners for $725mn.
- E.ON completed its acquisition of OVO following CMA approval.
- Landsec paid £95mn for a further 10% of Bluewater shopping centre, taking its stake to 74%.
Thanks for reading. If you’re interested in working together on your next M&A deal, feel free to reach out on LinkedIn.
Share your views on data room prices for a chance to win $150
One M&A advisor recently received a €90,000 invoice from his virtual data room provider, nearly four times the original quote. We suspect he’s not alone.
We’re surveying dealmakers across the M&A Community to find out how common hidden VDR costs really are. Share your experience in just two minutes.
As a thank you, everyone who takes part will be entered into a prize draw for a $150 Amazon voucher. All responses are confidential.
Weekly summary | 16.10.2026
We tracked 36 deals involving UK and Irish companies this week, 33 in the UK and three in Ireland. Energy led the way with ten transactions, ahead of technology with seven, while business services and industrials added six each.
Energy: wind, solar and the North Sea
Offshore wind was the busiest corner. Five Estuaries changed hands twice: Copenhagen Infrastructure Partners bought a 25% stake from a Macquarie-led consortium, and RWE confirmed the sale of its 33.3% lead stake to EDF.
Ørsted also took full ownership of Gunfleet Sands for about £15mn, while Ares bought into Statera’s 1.9GW flexible energy portfolio. Oil and gas kept pace too, with Shell taking 30% of Bay du Nord and Drilling Tools International agreeing to buy Aberdeen-based Saltire.
Mid-market, not mega deals
In contrast to this week’s big-ticket editorial, most deals in the tracker were mid-sized. The largest disclosed value was DCC’s $725mn sale of its tech arm Nexora to One Equity Partners, followed by Landsec’s £95mn move to raise its Bluewater stake to 74%.
Traffic in both directions
UK buyers were active abroad: Zotefoams bought in the US, EG On The Move in France, Constellation Cold Logistics in Norway and Synova in Denmark. Inbound, Accenture, ZEISS and Sika all picked up UK specialists.
Services keep consolidating
Six business services deals point to steady buy-and-build activity, from PLMR’s purchase of Social Communications Group to gbpartnerships’ double acquisition of DLP and Cass Design.
2026: The year of the big ticket?
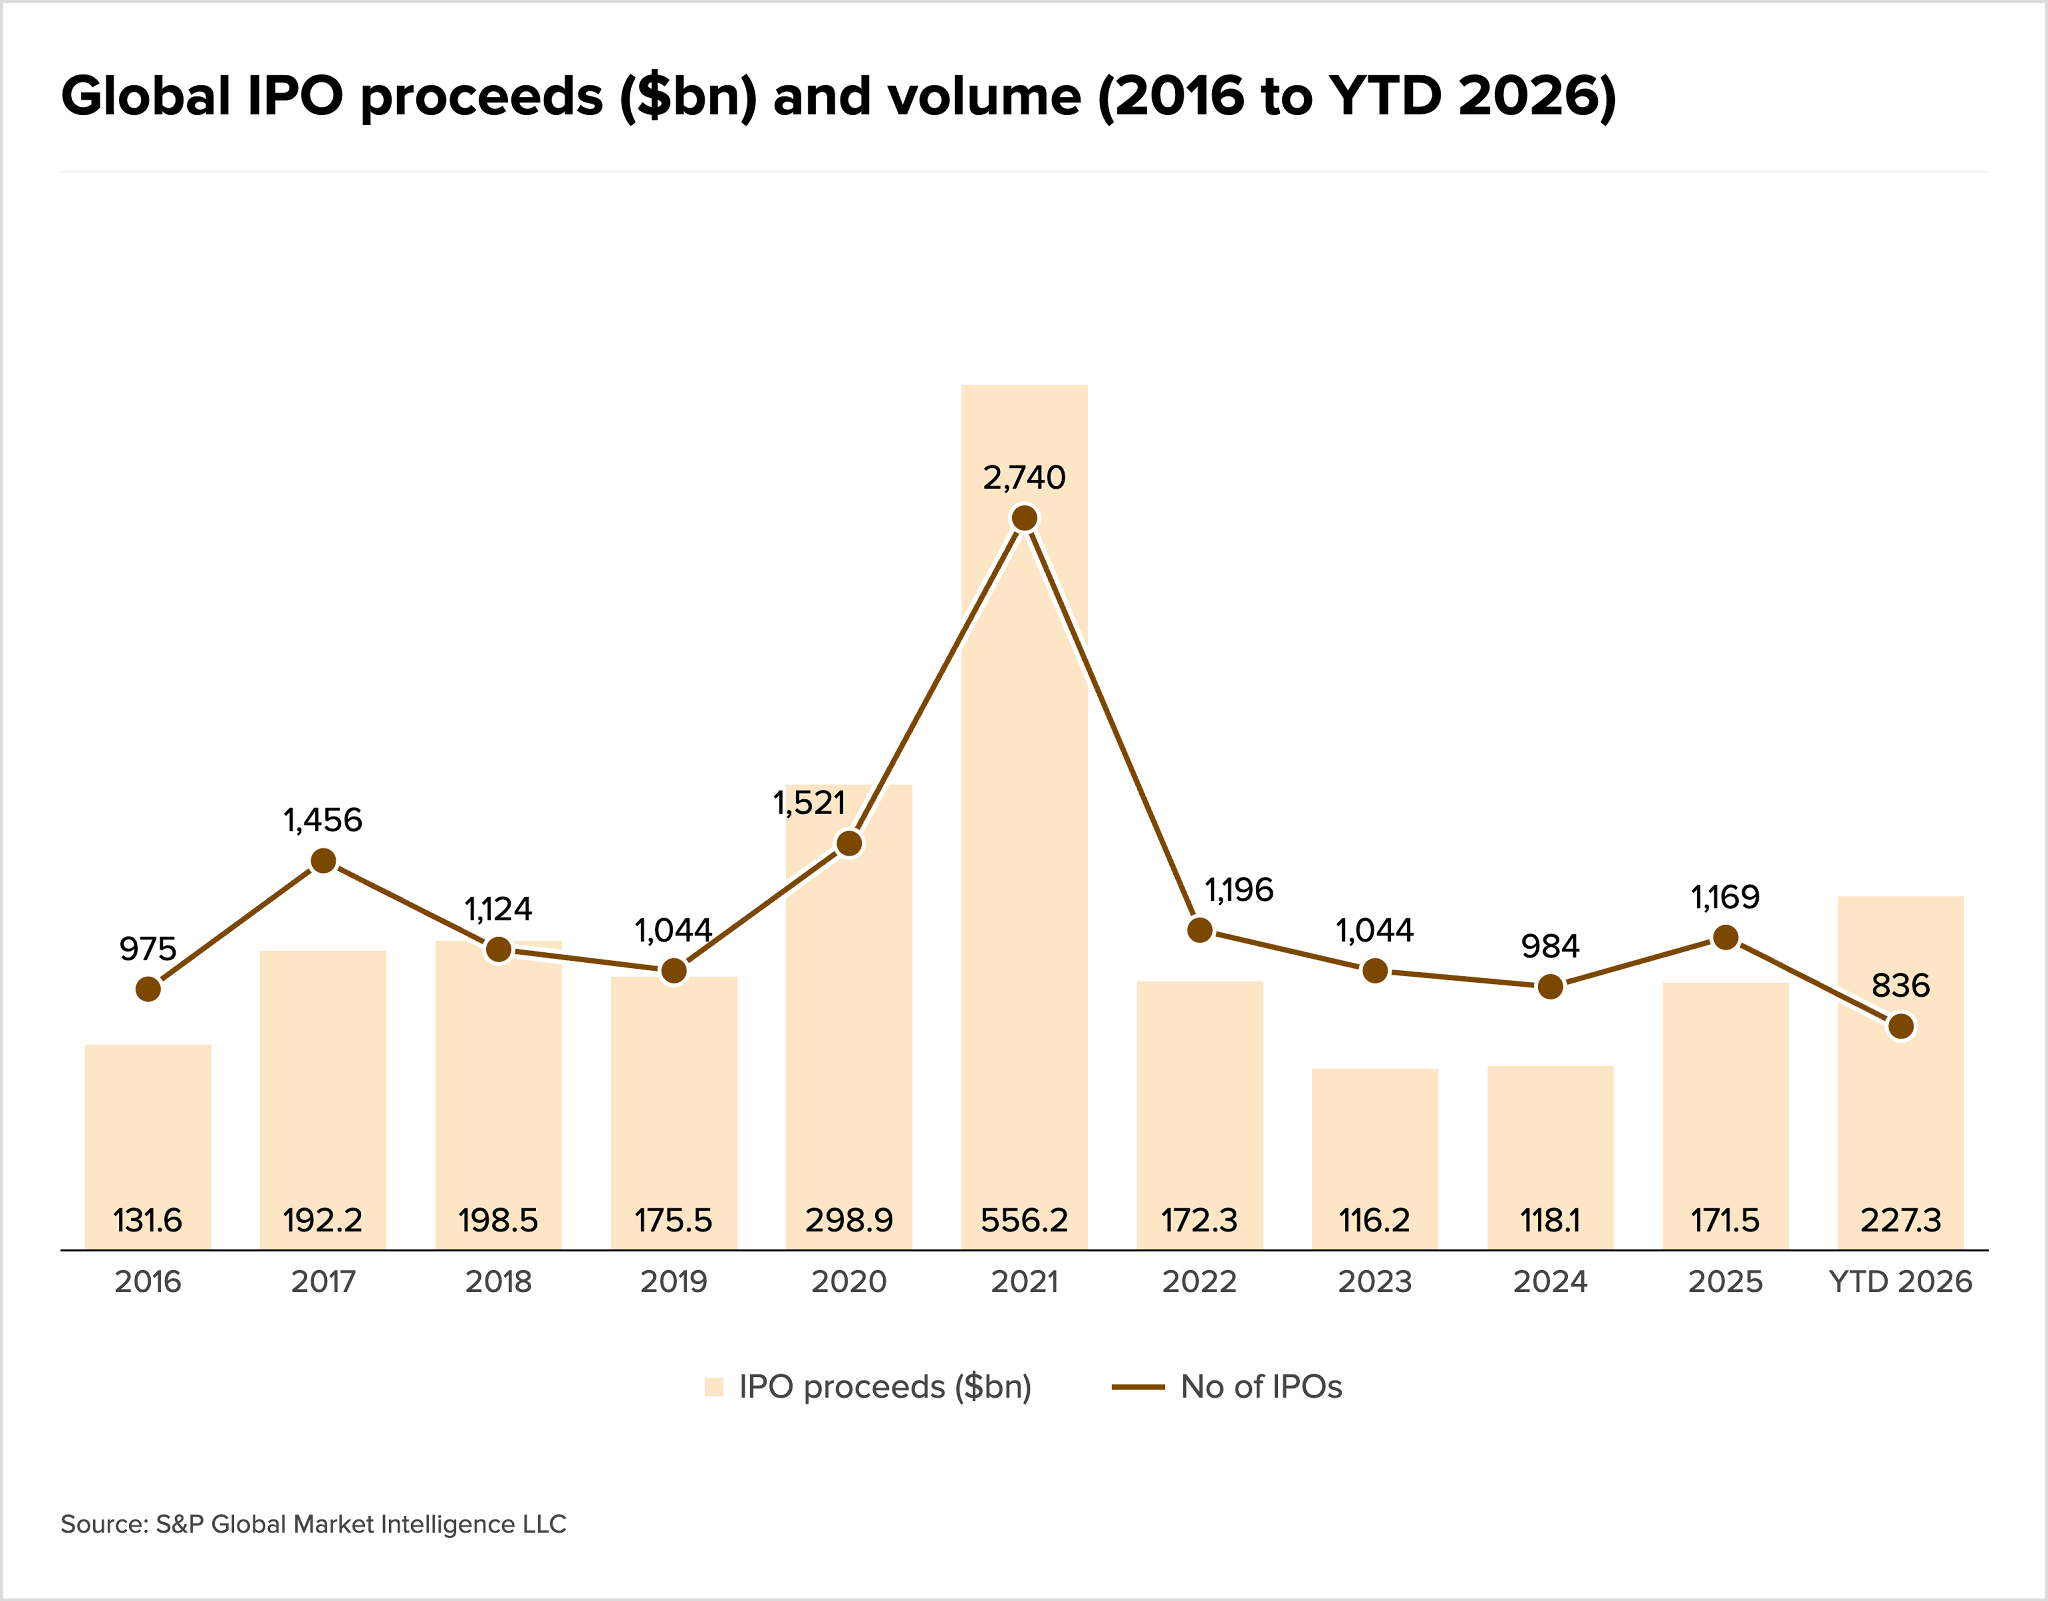
Global IPOs raised $227.3bn in the first nine months of 2026, according to PwC’s IPO Watch EMEA. That is already more than in any full year since 2021. But it came from just 836 listings.
The maths is simple:
- 2021: 2,740 IPOs, average size around $200mn
- 2025: 1,169 IPOs, average size around $150mn
- 2026 YTD: 836 IPOs, average size around $270mn
Fewer companies are going public. The ones that do are much larger.
M&A tells the same story
WTW’s latest Quarterly Deal Performance Monitor shows the same shift in completed deals above $100mn:
- 24 mega deals over $10bn closed in the first nine months, the strongest start to a year on record
- Nine of them closed in Q3 alone, up from three in Q2
- Quick deals, completed within 70 days of announcement, rose to 43% of Q3 transactions, from 35%
Bigger and faster, then. But not necessarily better.
Of the 200 deals completed in Q3, 60.5% of acquirers underperformed the MSCI World. On average, buyers trailed the index by 10.3 percentage points. As WTW’s Jana Mercereau puts it, speed “must not come at the expense of rigorous due diligence”.
The UK bucks the trend
While European acquirers underperformed their regional index by 5.0 points, UK buyers were the exception, delivering a strong outperformance.
What does that mean for dealmakers? Capital is concentrating on fewer, larger transactions, in public markets and in M&A alike.
But the UK result suggests disciplined buyers can still come out ahead, even when the clock is ticking.
Jobs Highlights
Rumour mill
- easyJet expects Apollo’s £5.7bn takeover to complete in early 2027, once the deal is structured to meet UK and EU airline ownership rules.
- Rightmove shares jumped 12% after Betaville reported takeover speculation involving a Gulf-backed trade buyer or a renewed approach from REA Group.
- Coca-Cola is again looking to sell Costa Coffee, months after calling off its previous sale process amid weak private equity interest.
- Irish-domiciled consumer health group Perrigo may have attracted takeover interest, according to Betaville.
- US chip-interconnect start-up Eliyan has drawn a takeover bid and held early talks with Arm as it seeks a valuation of around $3bn.
- Everton’s owner The Friedkin Group is weighing options including the sale of a controlling stake, less than two years after buying the club.
- ICG has hired Oakvale Capital to explore a sale of, or new investment in, Nottingham-based Buzz Bingo, which runs more than 75 clubs.
- Buyout firms are lining up exits from UK high street brands including PizzaExpress, Itsu, Waterstones and Third Space as dealmaking picks up.
- LSEG has confirmed talks to buy Permira-owned credit data firm Octus for about $3.5bn.
- Botswana is reportedly close to agreeing the size of its stake in De Beers as Anglo American pushes ahead with the sale of the diamond miner.
- Activist investor Ancora is pushing self-storage group Big Yellow to explore a sale, after takeover talks with Blackstone ended last year.
- Scottish Oriental Smaller Companies Trust launches a strategic review, including a possible combination with another investment company, with Investec advising.
Regulatory
- The European Commission fines Kingspan €40mn for providing misleading information during its review of the abandoned takeover of Slovenian rival Trimo.
- Macquarie offers to sell part of Energy Assets Group’s non-domestic gas metering business to resolve CMA concerns over its takeover of EAG.
- The CCPC is reviewing Musgrave’s acquisition of four Nally’s SuperValu stores in Kildare and Meath, with a decision due by 23 November.
- The CMA is consulting on undertakings from the Co-operative Group that would spare its completed takeover of The Southern Co-operative a Phase 2 investigation.
- Central Asia Metals receives Kazakh approval for its all-share acquisition of ASX-listed Cygnus Metals.
Job moves
- Former Davies Group corporate development executive Seetal Patel will lead the new London-based M&A department of claims management group MSA Mizar.
- WPP appoints McCann’s Tyler Turnbull as CEO of WPP Creative, succeeding Jon Cook.
- hVIVO appoints former Futura Medical executive Angela Hildreth as CFO from 18 November.
- Concept Life Sciences names former Selvita drug discovery head Dr Adrijana Vinter as chief executive.
- Former BDO M&A partner James Fieldhouse joins HURST Corporate Finance as a partner, focusing on business services and TMT.
IPOs
- Windscreen repair group Belron has picked banks for an Amsterdam IPO that could value it at more than €30bn.
- Revolut CEO Nik Storonsky says the fintech favours a US primary listing if it goes public.
- Scancell is set to list on Nasdaq through its merger with Neuphoria Therapeutics, with shareholders voting on the deal on 20 October.
- AI sound design firm SecondPass plans to list on AIM, aiming to raise up to £5mn.
- Airtel Money starts trading on the London Stock Exchange after pricing its IPO at £1.96 a share, valuing the African mobile money business at about £5.3bn.


