
 Daniel Black
If UK M&A had a motto this autumn, it would be “fewer, but bigger”.
Deal value has almost doubled this year, yet the number of deals keeps shrinking. In this week’s editorial, I dig into BCG‘s latest report to explain why capital is piling into a handful of large transactions, and what it will take for the rest of the market to catch up.
The good news? Buyers with conviction are paying up, and the mid-market could be next in line.
This week’s news played right into the theme. A £1.85bn take-private moved closer to the finish line, Nuveen closed its Schroders takeover, two bid battles kept boardrooms busy, and even Dragons’ Den star Peter Jones cashed out, selling Jessops to AO World.
Our Deals Tracker logged 24 transactions, with tech leading the way, Irish renewables on a roll and foreign buyers behind most UK deals. Here are three to start with:
- Veritas Capital is on course to complete its £1.85bn takeover of Bodycote after rival bidder CVC walked away.
- Harworth accepted a £632m offer from Peel, handing the regeneration specialist to one of the North West’s best-known property groups.
- Genel Energy outbid DNO with a $436m offer for Capricorn Energy, and the board switched sides to back it.
Thanks for reading, and connect with me on LinkedIn if you want to discuss how I can help with your next M&A deal,
Do you think VDR prices are a rip off?
One M&A advisor recently received a €90,000 invoice from his virtual data room provider, nearly four times the original quote. We suspect he’s not alone.
We’re surveying dealmakers across the M&A Community to find out how common hidden VDR costs really are. Share your experience in just two minutes.
As a thank you, everyone who takes part will be entered into a prize draw for a $150 Amazon voucher. All responses are confidential.
Week Summary | 02.10.2026
This week’s Deals Tracker captures 24 transactions across the UK and Ireland. Technology was the busiest sector with five deals, closely followed by energy, industrials and professional services with four each.
The tech deals spanned AI storage, cyber security, virtual reality and rail software. US buyers stood out: NetApp is set to acquire Manchester-based PEAK:AIO, and IBM picked up cyber specialist Logiq Consulting.
Ireland punched above its weight in energy. Lirion Power, Elgin Energy and Octopus added a combined 320MW of Irish wind and solar capacity. Statkraft also completed the sale of its UK green hydrogen portfolio to Norway’s Kentron Green Nordic.
Professional services stayed busy at the smaller end, with law, accountancy and communications firms consolidating. Financial services added three deals, including ANV’s purchase of Car Care Plan and Standish’s move for fund administrator NCM.
Two patterns stand out:
- Foreign buyers were behind 12 of the 19 UK deals, seven of them from the US. That echoes the inbound demand in this week’s editorial.
- Price tags were rare: only three deals disclosed a value.
Beyond the tracker, two bid battles are still live. Genel Energy has outbid DNO for Capricorn Energy, and Tribal Group now faces rival offers from Main Capital Partners and Jenzabar.
UK M&A isn’t recovering. It’s concentrating.
Big deals are back in the UK. A broad recovery isn’t, at least not yet.
BCG’s 2026 M&A Report, published last week, puts numbers on the split. In the first seven months of 2026:
- Deal value almost doubled, to $235.3bn from $119.0bn
- Deal volume fell to 1,763 transactions, from 2,272
- 65 deals above $500m generated 88% of the value
- The average large deal doubled in size, from $1.6bn to $3.2bn
The UK remains Europe’s largest M&A market, now with 37% of European deal value (up from 29%). Foreign buyers are back too: inbound deals for larger UK companies are at levels last seen in 2021–2022.
PwC’s mid-year figures tell the same story in sterling. H1 value more than doubled to £134.7bn, while volume fell 12.6% to 1,302 deals, the lowest point on the chart below. The top 10 deals made up about two-thirds of the value.
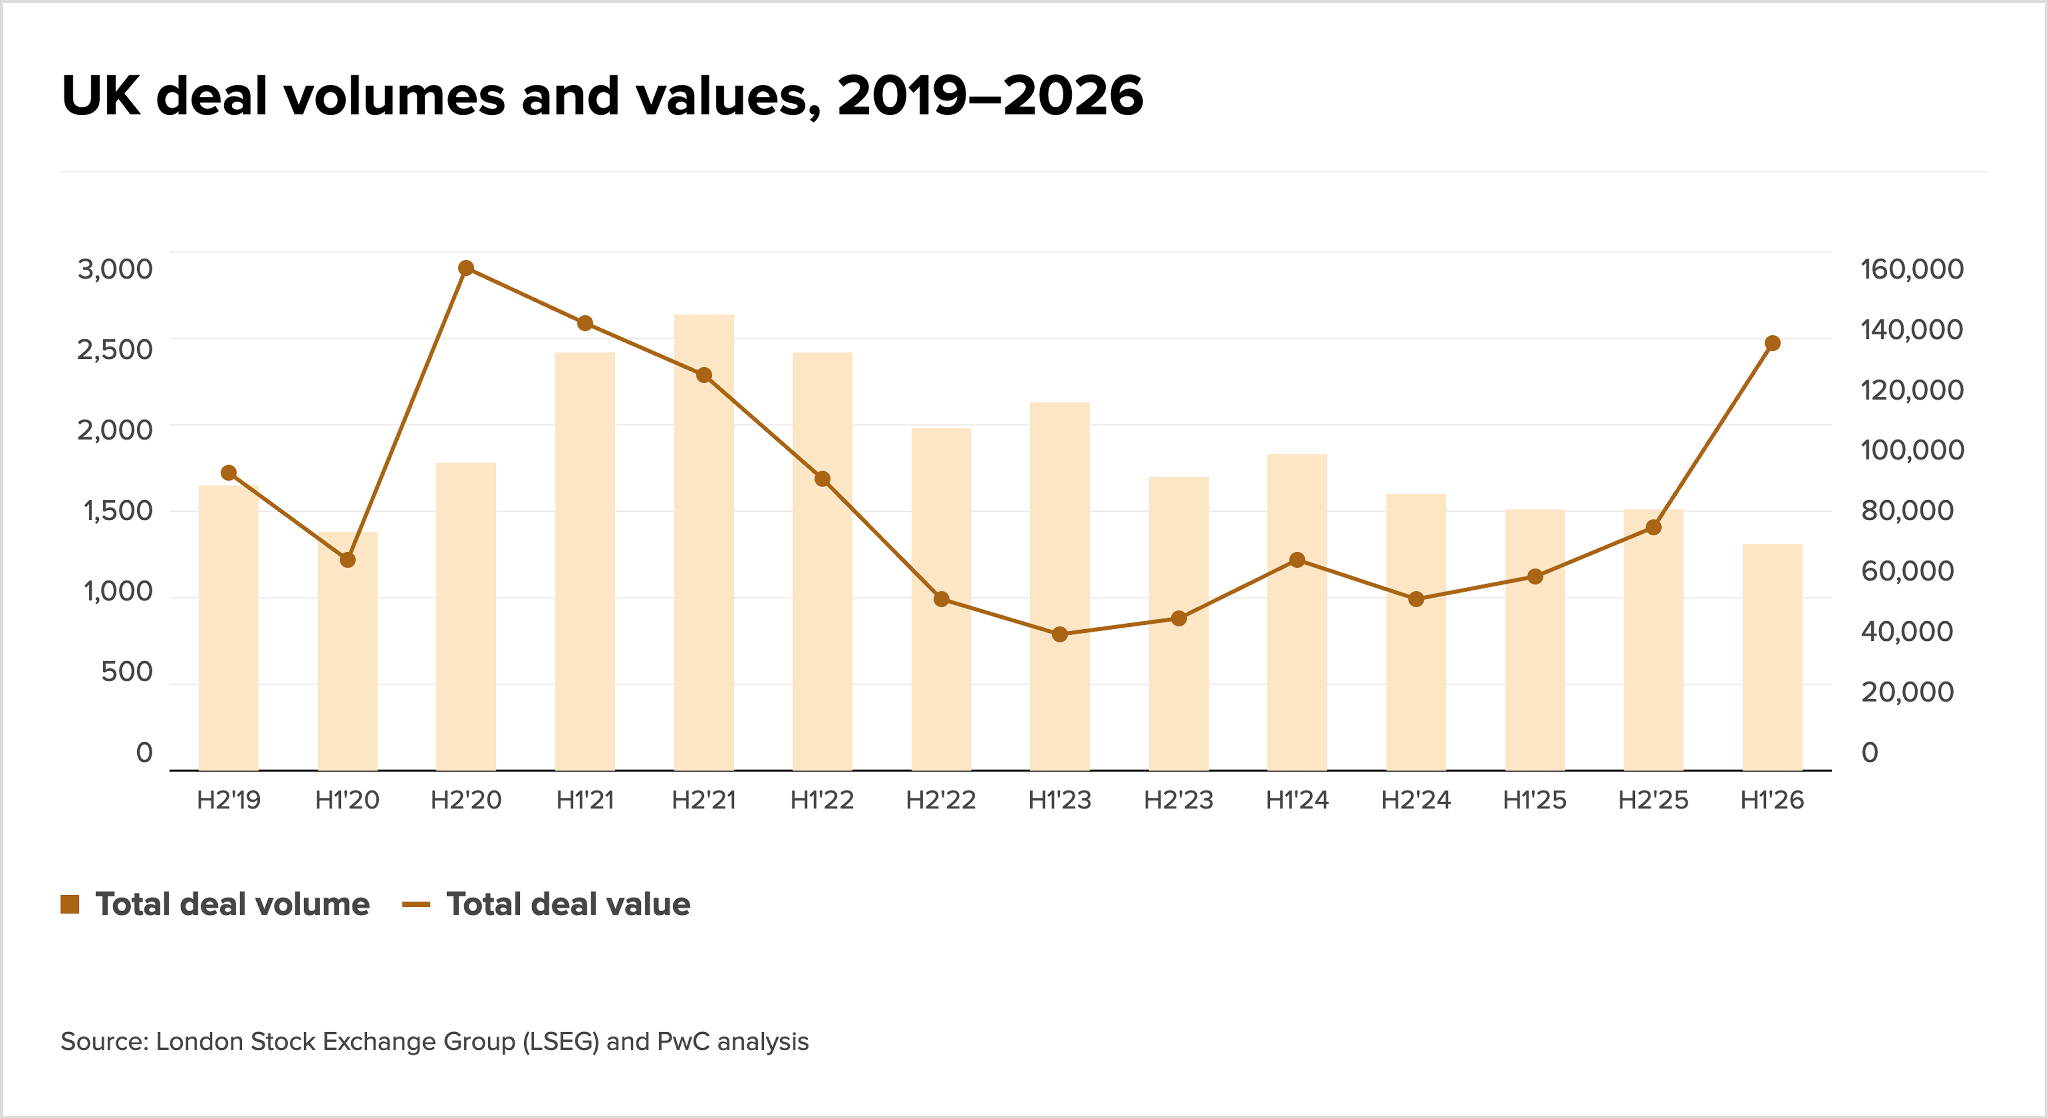
Capital is abundant. Conviction is scarce.
Buyers pay what PwC calls a “Concentration Premium” only for differentiated assets with clear strategic fit. Certainty of execution increasingly beats price. PwC’s sector heatmap shows where that conviction is landing: in H1 2026, deals above £5bn lit up in consumer markets and financial services.
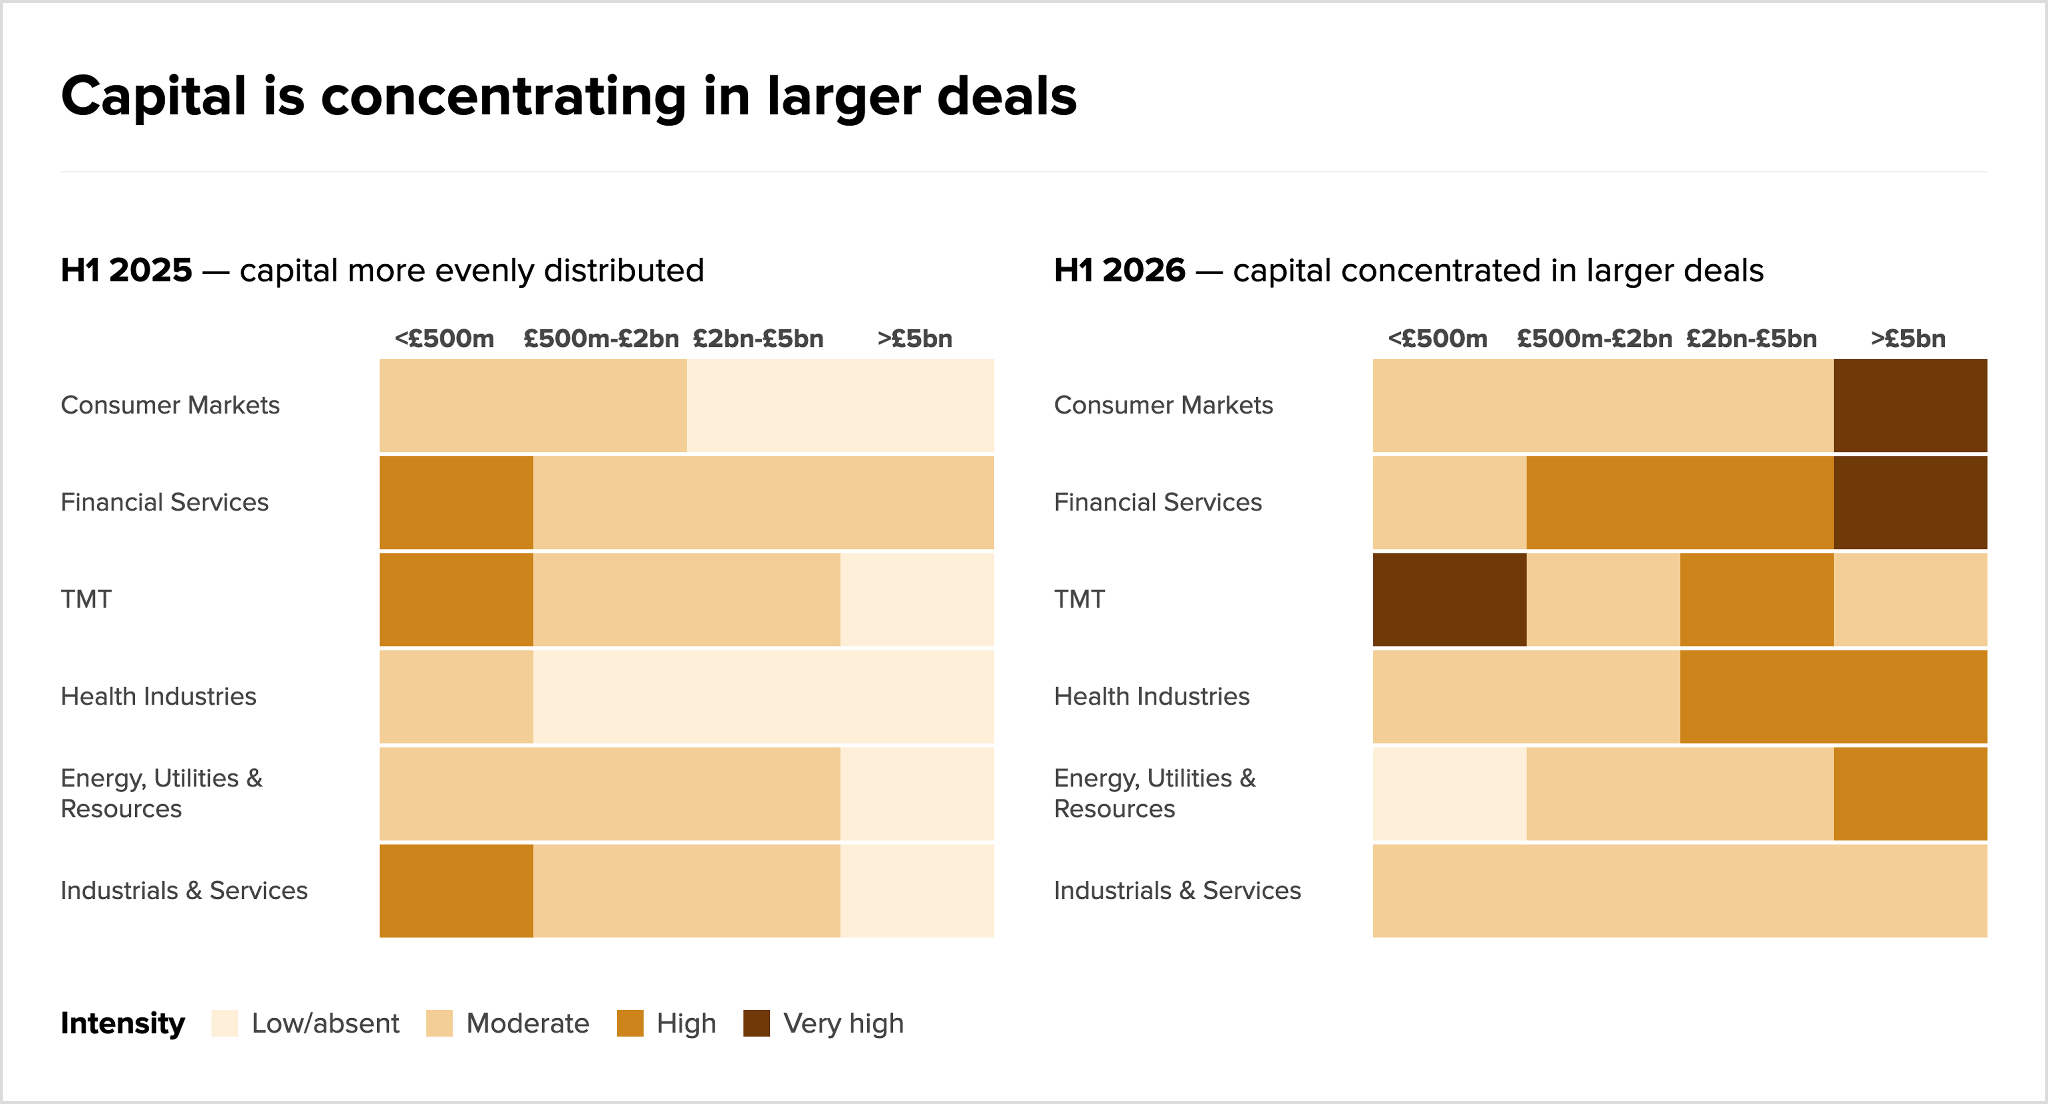
And certainty is far from guaranteed. According to BCG:
- About two-thirds of this year’s announced UK deal value is still pending, including deals involving Unilever, Beazley and Intertek.
- Three of the larger withdrawn deals were sponsor-led take-privates
- Sponsor-related value rose 49% to $105.8bn, but about a third came from exits to corporate buyers rather than new investment
My take: for the rest of 2026, completions matter more than announcements. If the pending megadeals close, confidence could filter down to the mid-market. That’s where the recovery has yet to arrive.
Jobs Highlights
Rumour mill
- Vesuvius shares surge after RHI Magnesita tables a cash-and-shares bid for the London-listed molten metal technology group.
- Bridgepoint and Astorg are weighing a sale of Irish fintech Fenergo that could value the client lifecycle software firm at more than £2bn.
- Checkit shares tumble 29% as takeover interest in the AIM-listed workflow software group fizzles out, despite its return to profit.
- Digital bank Monzo is in talks with Brazil’s Nubank about a potential sale, according to the FT.
- Epiris, already circling Gamma, is in talks to buy TalkTalk’s wholesale arm PXC for around £200m.
- Gordon Brothers wants £30m for Poundland, the discount chain it bought for less than £1, with Modella Capital and Fortress among the reported suitors.
- Pollen Street is exploring strategic options, including a potential take-private of the London-listed alternative asset manager.
- Tribal Group’s takeover turns into a bidding war as largest shareholder Jenzabar tables a rival cash offer, a day after Main Capital Partners raised its bid to £231.2m.
- Genel Energy outbids DNO with a $436m offer for Capricorn Energy, winning over a board that had previously backed its Norwegian rival.
Regulatory
- The CMA is minded to accept Co-op’s remedy packages for its Southern Co-op merger, a move that would spare the deal an in-depth Phase 2 probe.
- The CMA flags competition concerns over Macquarie Asset Management’s purchase of Energy Assets Group, giving the parties until 2 October to offer remedies or face a Phase 2 probe.
- The CMA opens a review of Vivisol’s planned acquisition of Air Liquide Healthcare’s UK home oxygen services business.
- Airbus offers divestments to secure Brussels backing for space merger
IPOs
- London-based Web3 learning app EasyA has confidentially filed for a direct listing in the US.
- Auditor RSM explores IPO to ward off private equity-backed rivals
- Fintech Zilch taps banks for IPO next year
- UK AI infrastructure group Nscale raises $3.36bn in pre-IPO convertible financing, paving the way for a stock market debut.


